Q3: Sentiment in the North East lifts but remains in negative territory.
- Business confidence in the North East rose from -10.2 in Q2 2026 to -3.7, but remained below the UK average and the region's historical norm.
- Companies reported strong annual domestic sales and exports growth, though they expect both to slow over the coming year.
- Geopolitical risk was the most widely cited rising challenge, followed by labour costs and energy costs, while regulatory concerns remained elevated.
- Employment growth picked up and ran ahead of the national average, but labour demand is predicted to cool.
- Input cost pressures are expected to persist, and firms raised their selling prices sharply, but strong profits growth is forecast to moderate.
- Capital investment and R&D both grew strongly over the past year, though companies plan to slow growth markedly.
Business confidence in North East
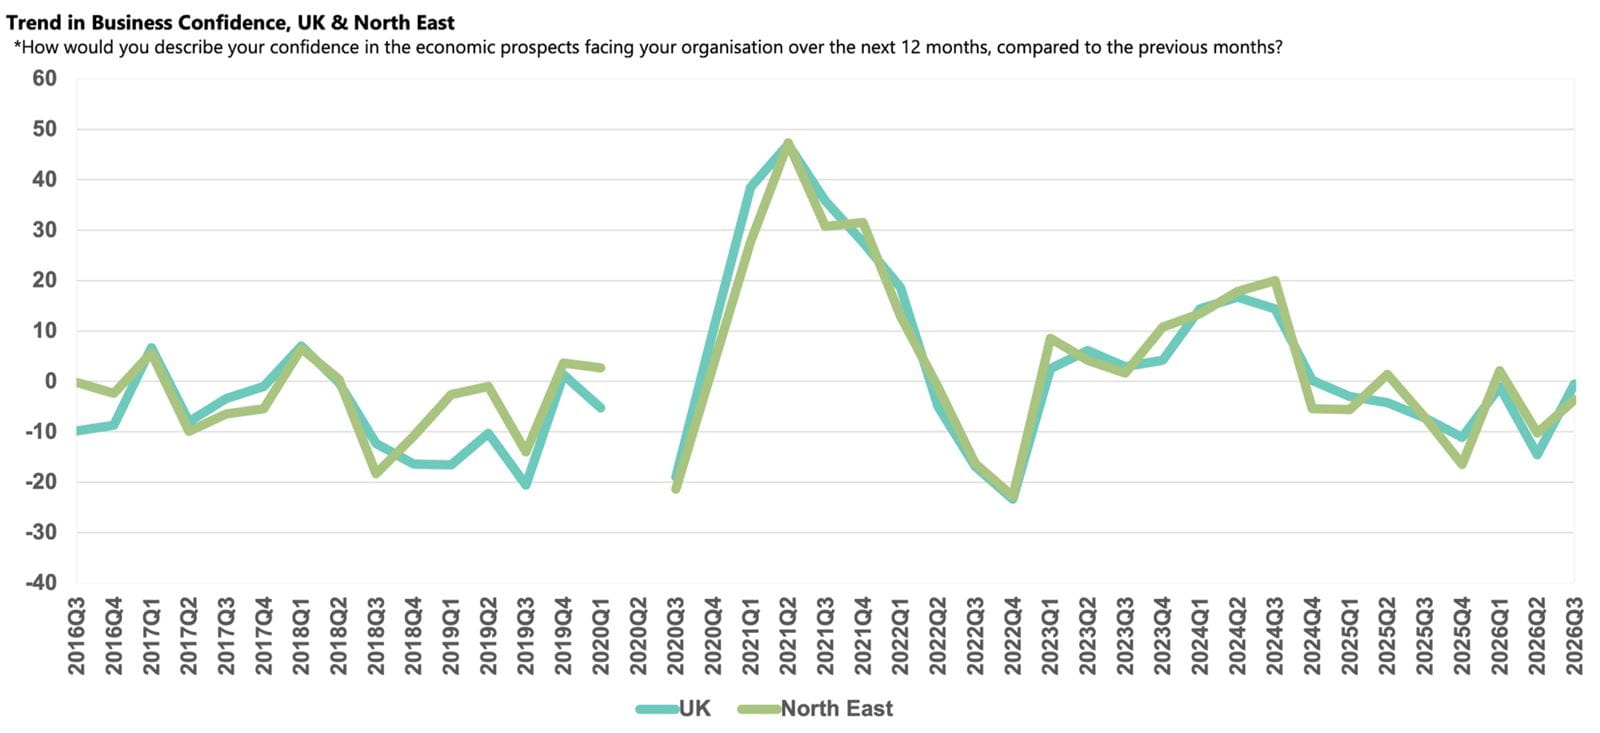
Business sentiment in the North East improved in Q3 2026, with the Business Confidence Index rising from -10.2 in Q2 2026 to -3.7. This was consistent with the broad-based recovery in confidence seen across the UK, as the economy proved more resilient than expected to the ongoing US-Iran conflict and disruption in the Strait of Hormuz. However, the region's score was in negative territory for the second consecutive quarter and sat below both the UK average (-0.5).
Confidence in the North East was likely supported by strong annual growth in domestic sales and profits, both of which outpaced the UK average. However, cost pressures continue to weigh on businesses. Energy costs were more widely cited as a growing challenge in the North East than in almost any other region, reflecting the regional economy’s relatively high dependence on the Manufacturing & Engineering sector.
Domestic sales and exports growth
Businesses in the North East reported robust annual domestic sales growth of 5.4% in Q3 2026 and notably above both the 3.6% rate recorded nationally and the region's historical norm (3.2%). Companies expect growth to moderate to 4.7% over the next 12 months, though this is higher than the 4.3% rise forecast nationally.
Annual exports growth picked up to 3.9% in Q3 2026, above the 2.8% rate recorded nationally and the region's historical norm (2.5%). However, export readings in the region have been somewhat volatile in recent quarters as companies react to changing global training conditions. Businesses are cautious about the outlook, anticipating that growth will slow to 3.2% over the coming year, below the 4.1% increase forecast for the UK.
Business challenges
With US-Iran tensions continuing through the survey period, geopolitical risk was the most widely cited rising challenge in the North East, reported by 57% of businesses, broadly in line with the UK average (58%). Energy costs remained a major concern for 52% of businesses, compared with 45% nationally, one of the highest proportions in the UK—reflecting the region’s greater exposure to elevated oil and gas prices.
Labour costs remained a growing challenge for 54% of businesses, broadly matching the UK average of 53%, despite concerns easing from the previous quarter. The region’s greater reliance on lower-paid roles increases its exposure to successive rises in the National Living Wage and employer National Insurance Contributions. Tax concerns also remained elevated, cited by 46% of businesses—more than twice the regional historical norm of 18% and above the UK average of 41%.
Regulatory concerns persisted as businesses adapted to the Employment Rights Act and Renters’ Reform Act. In Q3 2026, 51% of companies reported regulation as a growing challenge, unchanged from the previous quarter and above both the regional historical norm of 39% and the UK average of 46%. By contrast, concerns about customer demand fell to 30%, below the regional historical norm and national average of 36%. However, nearly one in five businesses (19%) cited government support as a rising issue—the highest share across the UK. This may reflect growing expectations that the new Prime Minister’s increased focus on devolution will deliver more locally tailored support for North East businesses, particularly in skills, infrastructure and investment.
Labour market
Annual employment growth in the North East picked up to 1.9% in Q3 2026, the fastest rate since Q3 2024 and well ahead of both the 0.7% rise recorded nationally and the region's historical norm (1.3%). However, anecdotal evidence suggests that companies in the region are delaying or avoiding replacement recruitment and instead using technology to increase their capacity. This view tallies with the latest BCM result which shows that businesses in the North East expect jobs growth to slow to 1.2% over the next 12 months, below the 1.5% rise forecast nationally.
Annual salary growth eased slightly to 2.9% in Q3 2026, broadly matching the UK average of 2.8% but remaining above the region’s historical norm of 2.2%. Despite slower workforce expansion, companies expect wage growth to accelerate to 3.2% over the coming year, compared with 2.6% nationally. This may indicate that firms are using technology to support productivity while prioritising the retention of existing employees over increasing headcount. Expectations may also reflect statutory wage rises and delayed pay settlements.
With employment demand expected to weaken, skills shortages are less of a concern for firms than usual. Although citations of limited management and non-management skills availability rose from the previous quarter to 10% and 15% respectively, both remained below their historical norms of 14% and 21%.
Input and selling prices, and profits growth
Annual input price inflation in the North East eased to 3.7% in Q3 2026, slightly below the UK average (3.9%) but still above the region's historical norm (2.8%). Unlike overall expectations across the UK, businesses in the region do not expect cost pressures to ease next year, predicting input price inflation of 3.8% which is well above the 2.9% rise forecast nationally.
Companies continue to pass some of their higher costs on to customers. They reported that they raised their selling prices by 3.0% in the year to Q3 2026, the fastest rate since Q1 2025 and one of the highest in the UK, running ahead of both the UK average (2.2%) and the region's historical norm (1.8%). Businesses intend to maintain a similar pace of price growth over the next 12 months, planning an increase of 2.8%, above the 2.1% rise expected nationally.
Firms in the North East recorded strong annual profits growth of 6.2% in Q3 2026, well above the UK average (3.3%) and the region's historical norm (3.0%). Companies expect profits growth to moderate to 4.5% over the next 12 months, in line with the UK projection. However, many of these projections were formed before the renewed US/Israel-Iran hostilities in September which caused a spike in oil and gas prices and increased global uncertainty.
Capital investment and R&D
Companies in the North East recorded solid annual capital investment growth of 3.3% in Q3 2026, the joint-fastest rate recorded in the UK, and above the 2.3% rate recorded nationally. However, businesses plan to slow investment growth to 1.6% over the coming year, below the 2.0% rise anticipated across the UK and the region's historical norm (2.4%).
Annual R&D growth picked up to 3.0% in Q3 2026, the fastest rate since Q1 2020 and above both the UK average (2.3%) and the region's historical norm (1.9%). This may reflect a focus by UK businesses on productivity and efficiency gains to mitigate rising costs, as highlighted by the latest ICAEW pulse survey. However, companies in the North East expect R&D growth to slow to 0.9% over the next 12 months, below the 1.9% rise forecast nationally.
UK results
The UK Business Confidence Index rebounded to -0.5, from -14.6 in Q2, but remained negative for a seventh consecutive quarter. Current sales and profits proved resilient, but firms downgraded their expectations for both over the next 12 months. Geopolitical risk remained the leading challenge, while elevated input and labour costs continued to put pressure on margins. Energy costs, regulations and the tax burden remain significant challenges. The rebound was broad but uneven: confidence rose in every sector, IT & Communications was the most positive, while Property and Construction remained deeply negative.
The latest quarterly findings are based on the period 13 July to 21 September 2026.