Q3: Yorkshire & Humber business confidence remains positive and above the UK average.
- Yorkshire & Humber’s Business Confidence Index held at +2.1 in Q3 2026, outperforming the UK average of -0.5.
- Despite slower domestic sales and exports growth, firms expect both will improve over the coming year.
- Labour costs were the leading challenge, with geopolitical risks, energy costs, taxation uncertainty and weakening customer demand all prevalent concerns.
- Employment growth was subdued and businesses expect hiring to remain weak, with wage inflation predicted to rise.
- Input cost and selling price inflation slowed, while weak sales and elevated costs constrained profits growth, but firms expect profitability to improve.
- Capital investment and R&D growth weakened, with global uncertainty and concerns about returns weighing on future spending plans.
Business confidence in Yorkshire & Humberside
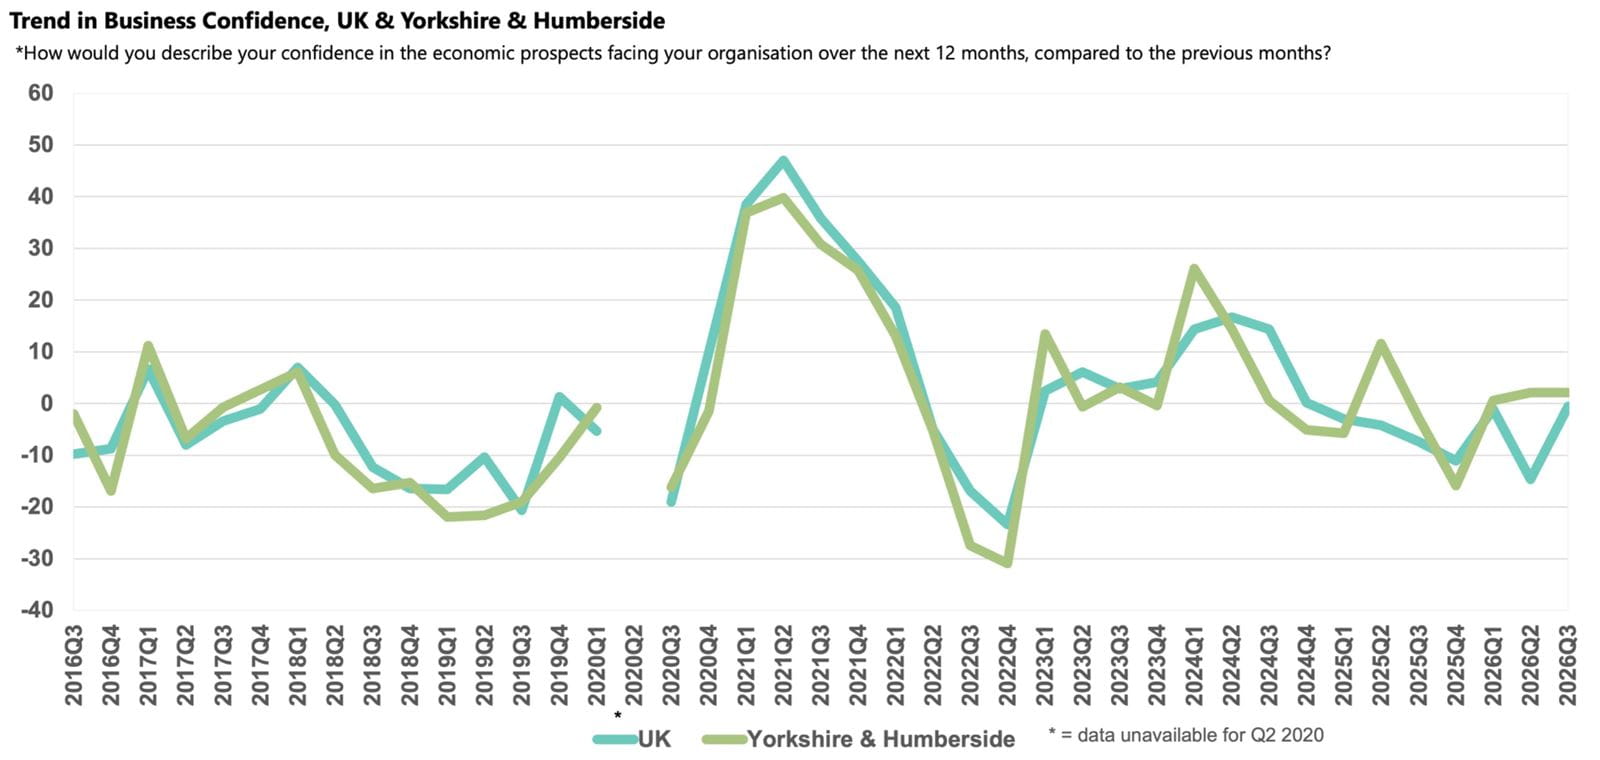
Yorkshire & Humber was the only region or UK nation not to report an uplift in confidence in Q3 2026, but the Business Confidence Index held steady in positive territory at +2.1. Sentiment in the region remained ahead of the UK average (-0.5) but was again below its regional historical average (+4.6).
Despite escalating conflict in the Middle East, businesses in Yorkshire & Humber remain upbeat. A strong domestic sales outlook and easing input cost inflation underpin robust profit expectations. But risks loom large: worsening US–Iran relations, higher inflation and UK political uncertainty could impact the outlook, as businesses look ahead to the Autumn Budget.
Domestic sales and exports growth
Annual domestic sales growth slowed for the second consecutive quarter in Q3 2026, easing to 3.4%, marginally lagging the national average increase of 3.6%. While companies in the region have lowered their projections for the coming year, they are the most optimistic of any UK region, anticipating a marked uplift to 5.3%, which exceeds the 4.3% growth predicted across the UK as a whole and is nearly double the region’s historical norm (2.9%).
Heightened global uncertainty weakened external demand during the survey period, particularly in the region’s important Manufacturing & Engineering sector, as fuel prices surged. ICAEW members also reported that the continued closure of the Strait of Hormuz constrained trade with the Middle East. Consequently, annual exports growth fell for a second consecutive quarter in Q3 2026, to 1.5%, the weakest rise among UK regions and just over half the region’s historical average (2.7%). While firms in the region still anticipate an uplift in growth over the coming year, they have revised their outlook down significantly compared to the previous quarter and now project a rise of 3.4% over the next 12 months, below the national average forecast of 4.1%.
Business challenges
A main theme reported by members in the region is that they continue to struggle with the increase in employment costs following the consecutive uplifts in National Minimum Wage in recent years along with the burden posed by increased employers’ National Insurance Contributions. Labour costs were the most widespread concern among businesses surveyed in Yorkshire & Humber, with 60% citing this as rising a challenge, above the national average of 53%.
As in most other regions, the prolonged conflict in the Middle East meant that geopolitical risk remained at the forefront of concerns for Yorkshire & Humber businesses in Q3 2026. Of the companies surveyed in the region, 57% reported the issue as a growing challenge, which is in line with the national average (58%). The impact of the associated spike in oil and gas prices was evident in BCM, with energy costs cited by 45% of businesses as a rising challenge, matching the UK average (45%).
Tax concerns have eased but remain significant, affecting 49% of businesses in the region. The increased burden and uncertainty over possible tax rises in the Autumn Budget have prompted many businesses to delay investment decisions pending greater clarity. Meanwhile, citations for customer demand ticked up above the historical norm (40%) in Q3 2026, with 43% of businesses reporting the issue as a rising concern over the past year, above the UK as a whole (36%).
Labour market
Heightened global trade uncertainty and increased hiring costs and complexity following the Employment Rights Bill’s introduction in May, weakened labour demand in Yorkshire & Humber. Employment grew by just 0.1% in the year to Q3 2026, among the lowest rates in the UK and ahead only of Scotland, where employment declined. Businesses expect growth to improve to 0.6% over the next year, below the region’s historical average of 1.0% and the weakest outlook among UK regions and nations.
Perhaps unsurprisingly, concern about the availability of both management (6%) and non-management (12%) skills fell significantly compared to the previous quarter, with citations for both well below their respective historical norms (14% and 19%).
Despite sluggish employment growth, annual wage inflation remained above the historical norm (2.3%) in Yorkshire & Humber in Q3 2026, at 2.5%. Businesses predict salary growth will increase slightly over the next 12 months to 2.7%, comparable to the 2.6% rise projected across the UK.
Input and selling prices, and profits growth
Annual input price inflation slowed to 3.8% in Q2 2026, broadly matching the UK rate (3.9%). Firms in the region expect input cost growth to ease significantly to 2.1% over the next year, below the region’s historical average of 2.8% and the weakest forecast among UK regions. However, the continued closure of the Strait of Hormuz poses a significant risk to these forecasts, particularly as Brent crude oil surpassed $100 per barrel in the final weeks of the survey and this outlook will likely be revised in the coming months.
The BCM indicated that Yorkshire & Humber businesses are absorbing some input cost increases rather than passing them on to customers. They reported lifting their selling prices by 2.2% in the year to Q3 2026, equaling the UK average. Businesses expect to reduce the pace of price rises to just 1.6% over the coming year. This projected increase is lower than other UK regions but equals to the region’s historical norm.
Amid elevated inflation and weakened domestic sales and exports growth, profits growth in the region slowed to just 1.5%. This increase was the weakest rise of any UK region or nation at less than half the UK average rate (3.3%). Businesses are optimistic that annual profits growth will surpass the region’s historical norm over the coming year (2.8%), predicting profits will rise by 4.9%.
Capital investment and R&D
Annual capital investment growth in Yorkshire & Humber eased slightly from the previous quarter in Q3 2026, to 1.8%, lagging both the national increase (2.3%) and the region’s historical norm (2.0%). With heightened global uncertainty, businesses in the region have serious concerns over the likely return on their investment and are planning to reduce investment growth to 1.4% over the next 12 months. This is one of the weakest projections across the UK and below the national forecast of 2.0%.
Unlike the wider UK, annual R&D growth in Yorkshire & Humber was weak at 0.9% in Q3 2026, approximately half of the region’s historical norm (1.7%) and among the lowest rises in the UK. Businesses plan to slow growth even further over the next 12 months, predicting the smallest increase of all UK regions at just 0.1%.
UK results
The UK Business Confidence Index rebounded to -0.5, from -14.6 in Q2, but remained negative for a seventh consecutive quarter. Current sales and profits proved resilient, but firms downgraded their expectations for both over the next 12 months. Geopolitical risk remained the leading challenge, while elevated input and labour costs continued to put pressure on margins. Energy costs, regulations and the tax burden remain significant challenges. The rebound was broad but uneven: confidence rose in every sector, IT & Communications was the most positive, while Property and Construction remained deeply negative.
The latest quarterly findings are based on the period 13 July to 21 September 2026.