Q3: Business confidence in the South West returns to positive territory as domestic sales growth picks up.
- Business confidence in the South West rose to +4.9 from -18.5 in Q2 2026, ahead of both the UK average (-0.5) and the region's historical norm (+3.2).
- Annual domestic sales growth picked up to its strongest rate since Q3 2024, and companies expect both domestic sales and exports growth to improve further.
- Labour costs overtook geopolitical risk as the most widely cited growing challenge, while concerns about customer demand, competition and late payment eased.
- Employment growth picked up but remained below the historical norm, while salary growth dropped to its lowest rate since Q4 2021.
- Input price and selling price inflation both eased, and profits growth slowed, but companies expect an improvement next year.
- Capital investment growth weakened but is expected to recover, while R&D spending accelerated sharply before a forecast slowdown next year.
Business confidence in South West
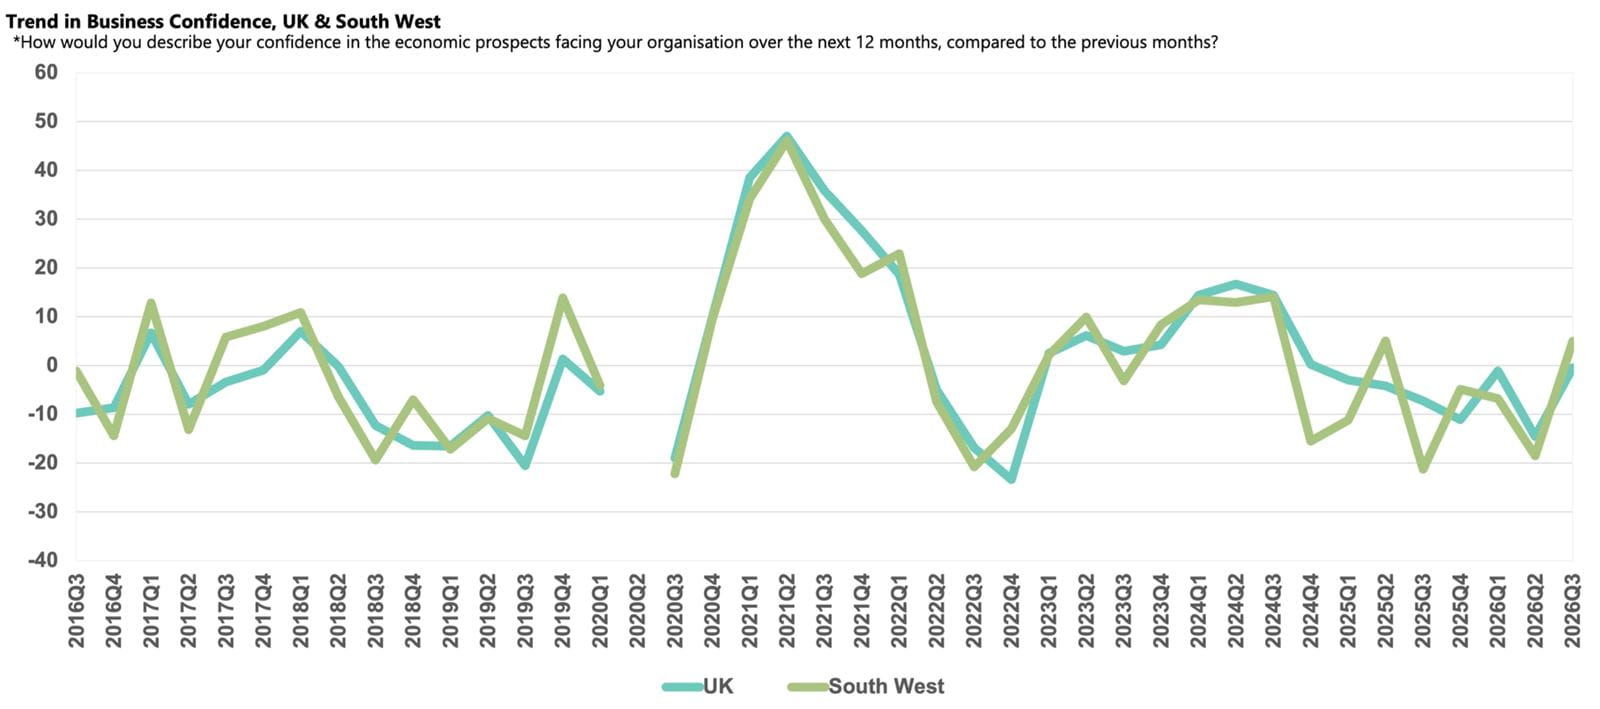
Sentiment in the South West improved markedly in Q3 2026, with the Business Confidence Index rising from -18.5 in Q2 2026 to +4.9. This was the region's first positive score and its highest reading since Q2 2025, placing the South West among the most confident parts of the UK, and above the national average (-0.5) and the region's historical norm (+3.2).
The improvement was consistent with the resilience shown by the wider UK economy to the ongoing US-Iran conflict and the disruption in the Strait of Hormuz. Businesses in the region reported a pick-up in domestic sales growth and fewer concerns about customer demand, competition and late payments, suggesting trading conditions became less challenging compared to last quarter. However, with rising labour costs still a widespread concern, South West companies remain cautious about their profit outlook.
Domestic sales and exports growth
Annual domestic sales growth picked up to 3.7% in Q3 2026, the strongest rate since Q3 2024. This was above the norm (3.1%) and broadly in line with the 3.6% rate recorded nationally. Companies in the region are also more optimistic about the year ahead than last quarter, predicting growth will rise to 4.4%, marginally ahead of the 4.3% rise expected across the UK.
Annual exports growth eased slightly to 2.6% in Q3 2026, close to the region's historical norm (2.7%) and just below the UK rate (2.8%). Despite continued geopolitical tensions, businesses have raised their expectations for overseas sales, predicting growth of 3.9% over the next 12 months, which is slightly below the 4.1% rise forecast nationally.
Business challenges
Geopolitical risk remained a major concern, cited by 54% of businesses amid continuing US–Iran tensions. However, this share fell from the previous quarter and remained below the UK figure of 58%. Energy costs were an increasing challenge for 37% of respondents, compared with 45% nationally, although the survey may not fully reflect September’s spike in wholesale gas and crude oil prices.
Domestic pressures also remained significant. Labour costs were the most widely cited growing challenge in Q3 2026, reported by 56% of businesses, slightly above the UK average of 53%. Regulatory requirements concerned 40% of respondents, in line with the region’s long-run average but below the national figure of 46%. The tax burden was cited by 35%, lower than the UK average of 41% but almost double the region’s typical rate of 19%.
There were also signs that trading conditions had become less difficult. Concerns about customer demand fell notably to 34%, below both its long-term regional rate of 39% and the UK figure of 36%. Marketplace competition was cited by 30% of businesses, compared with the regional norm of 34%. Responses for late payments also declined to 15%, below the region’s 22% benchmark and the national figure of 19%.
Labour market
BCM provides a picture of slowing labour market activity in the region, despite employment expanding by 1.1% in the year to Q3 2026, ahead of the 0.7% rate recorded nationally. Businesses expect jobs growth to ease slightly over the next 12 months, projecting a 1.0% rise, which is lower than both the 1.5% increase forecast across the UK and the region's historical norm (1.4%).
Meanwhile, salary growth slowed to 2.6% in the year to Q3 2026, its weakest rate since Q4 2021. This was below the UK rate of 2.8% but above the region’s norm of 2.3%. Businesses expect growth to remain at 2.6% over the coming year, matching the national forecast. Despite signs of slowing labour demand, 20% of businesses reported concerns about the availability of non-management skills, broadly in line with the regional average of 19% but among the highest shares in the UK and above the national figure of 15%.
Input and selling prices, and profits growth
Annual input price inflation in the South West eased to 3.9% in Q3 2026, matching the UK rate but remaining above its long-run average of 2.9%. Businesses expect cost growth to slow to 3.1% over the next year, slightly above the 2.9% national forecast, although recent energy price rises present an upside risk.
Selling price growth slowed to 2.1%, its weakest rate since Q3 2024. This was slightly below the UK rate of 2.2% but above the region’s norm (1.7%). South West firms plan to raise prices by 2.2% over the coming year, broadly matching the UK forecast of 2.1%.
Against this backdrop, annual profits growth slowed to 2.1%, its weakest rate since Q4 2025 and below both the region’s 3.0% benchmark and the UK rate of 3.3%. This is consistent with findings from an ICAEW pulse survey that found that 57% of businesses in the UK have absorbed higher costs over the past year by lowering their profit margins. However, while businesses in the region expect profits growth to recover over the next year, supported by stronger sales, their predicted rate of 3.9% is lower than the national forecast of 4.5%.
Capital investment and R&D
Annual capital investment growth in the South West slowed to 0.9% in Q3 2026, well below both the region's historical norm (2.0%) and the 2.3% rate recorded nationally. Businesses plan to lift investment growth to 2.0% over the next 12 months, matching both the national forecast and the region's historical norm.
R&D budget growth picked up to 2.2% in Q3 2026, its fastest rate since Q3 2023, above the region's historical norm (2.0%) and close to the 2.3% rate recorded nationally. This is in line with the national finding from the latest ICAEW pulse survey, that found more firms across the UK sought productivity and efficiency improvements to mitigate the rise in business costs. However, companies expect growth to slow to 1.1% over the next 12 months, lagging the 1.9% rise forecast nationally.
UK results
The UK Business Confidence Index rebounded to -0.5, from -14.6 in Q2, but remained negative for a seventh consecutive quarter. Current sales and profits proved resilient, but firms downgraded their expectations for both over the next 12 months. Geopolitical risk remained the leading challenge, while elevated input and labour costs continued to put pressure on margins. Energy costs, regulations and the tax burden remain significant challenges. The rebound was broad but uneven: confidence rose in every sector, IT & Communications was the most positive, while Property and Construction remained deeply negative.
The latest quarterly findings are based on the period 13 July to 21 September 2026.