Q3 2026: The ICAEW Economic Update Middle East, is a quarterly economic forecast for the region prepared directly for the finance profession.
Economic Update: Export recovery underpins a strong 2027 outlook
- Export recovery, particularly of energy, is set to drive a 6.8% rebound in GCC growth in 2027.
- Non-oil activity will also gain momentum, with consumers benefitting from improving confidence and easing pricing pressures.
- We project a substantial rebound in travel and tourism next year, though a full recovery is unlikely before 2028.
We expect the global economy to continue to weather the energy price shock resulting from the unresolved US conflict with Iran Global GDP is expected to grow by 2.9% in 2027, 0.2ppt less than we projected three months ago, albeit up from 2.6% this year.
Within the region, the past six months have seen an uneven cycle of escalation and de-escalation. We think this pattern will likely continue in the coming months, likely preventing trade and energy flows from returning to pre-war levels. That said, our baseline assumes that a combination of bilateral and multilateral agreements will gradually improve shipping flows into 2027.
On this basis, we forecast aggregate GDP growth of 6.5% for the Middle East in 2027, following an unparalleled 5.3% contraction this year (we projected a 4.1% contraction three months ago). Favourable base effects will mechanically boost next year’s growth rate but we also expect a substantial rebound in activity as this year’s disruption gradually unwinds.
These projections are consistent with our outlook for the GCC economies, which we expect will recover strongly next year after a dismal 2026. We forecast GCC GDP growth of 6.8% in 2027, following a 5.4% contraction this year (double the contraction we projected previously). We expect Saudi Arabia to be the largest contributor to the region’s rebound with GDP growth improving to 6.4%, from a 2.3% contraction this year. The sharp swing reflects primarily our expectation of gradual normalisation in the oil sector after activity was disrupted this year. The UAE is also set for a strong 2027, with growth forecast at 6.6%. Meanwhile we expect Qatar to record the region’s fastest expansion, at 11.5%, following a much weaker 2026. Qatar’s dependence on the Strait of Hormuz for energy exports has made it particularly vulnerable to the current disruption.
Chart 1: Real GDP growth
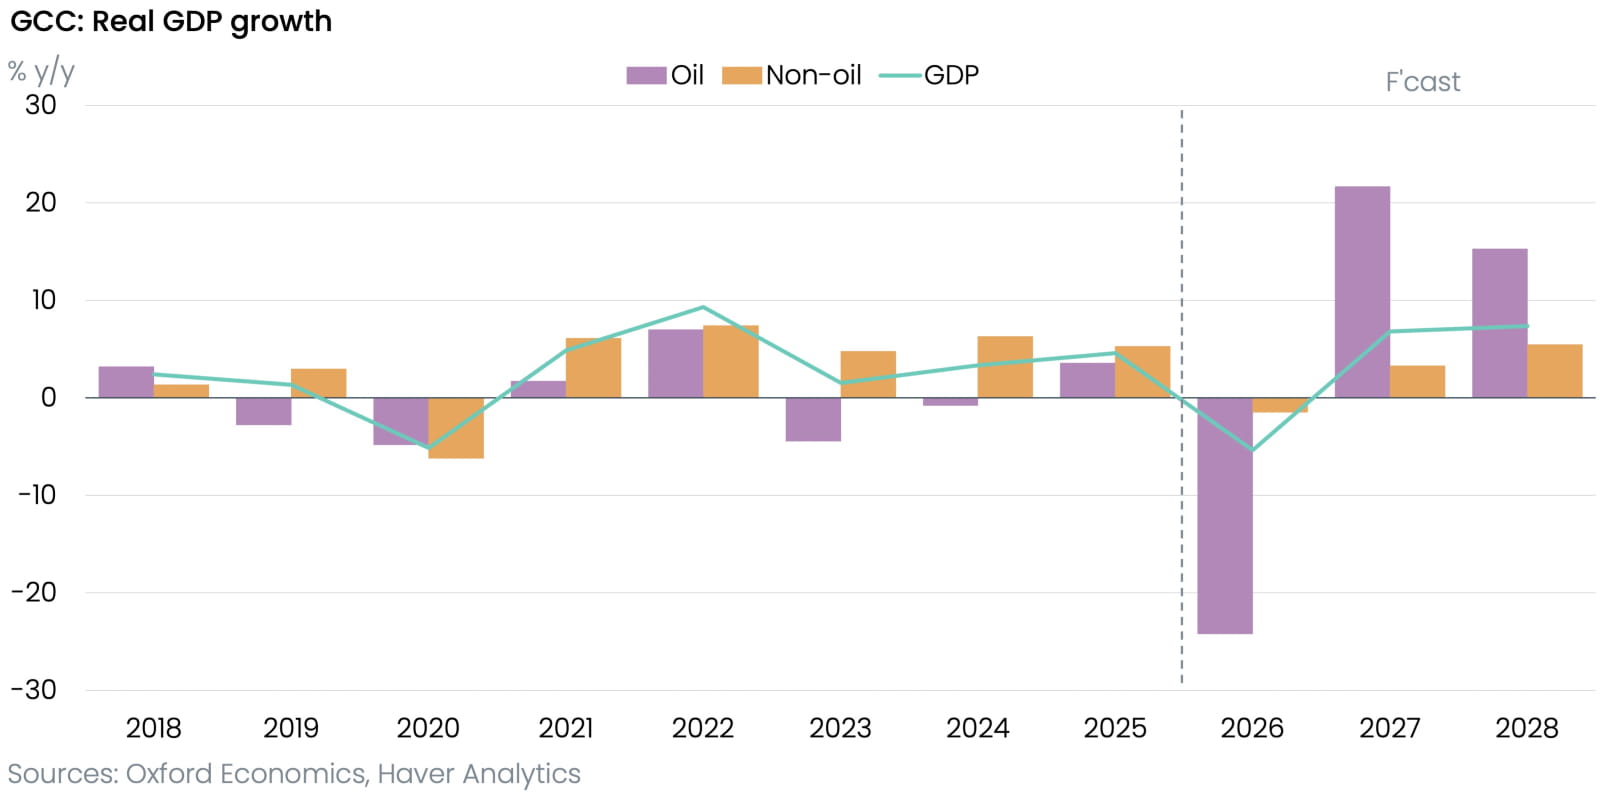
Our view of economic recovery in 2027 is heavily contingent on at least a partial normalisation of shipping flows through the Strait of Hormuz. There is no alternative to fully reroute energy exports and viable workarounds, such as Saudi Arabia’s shipments through the Red Sea have also come under pressure as geopolitical tensions have spread. Overall, we forecast the GCC’s hydrocarbon sector will rebound with 21.7% growth in 2027, following a contraction of 24.2% this year. The improvement will contribute about 70% of 2027 GDP growth in total.
Meanwhile, oil prices have been volatile, rising above $100 per barrel for the first time since July amid renewed US-Iran strikes on vessels in the Strait of Hormuz. We expect tensions and prices to remain elevated, with Brent oil trading above the mid-$80s well into 2027.
Chart 2: Non-oil GDP recovery
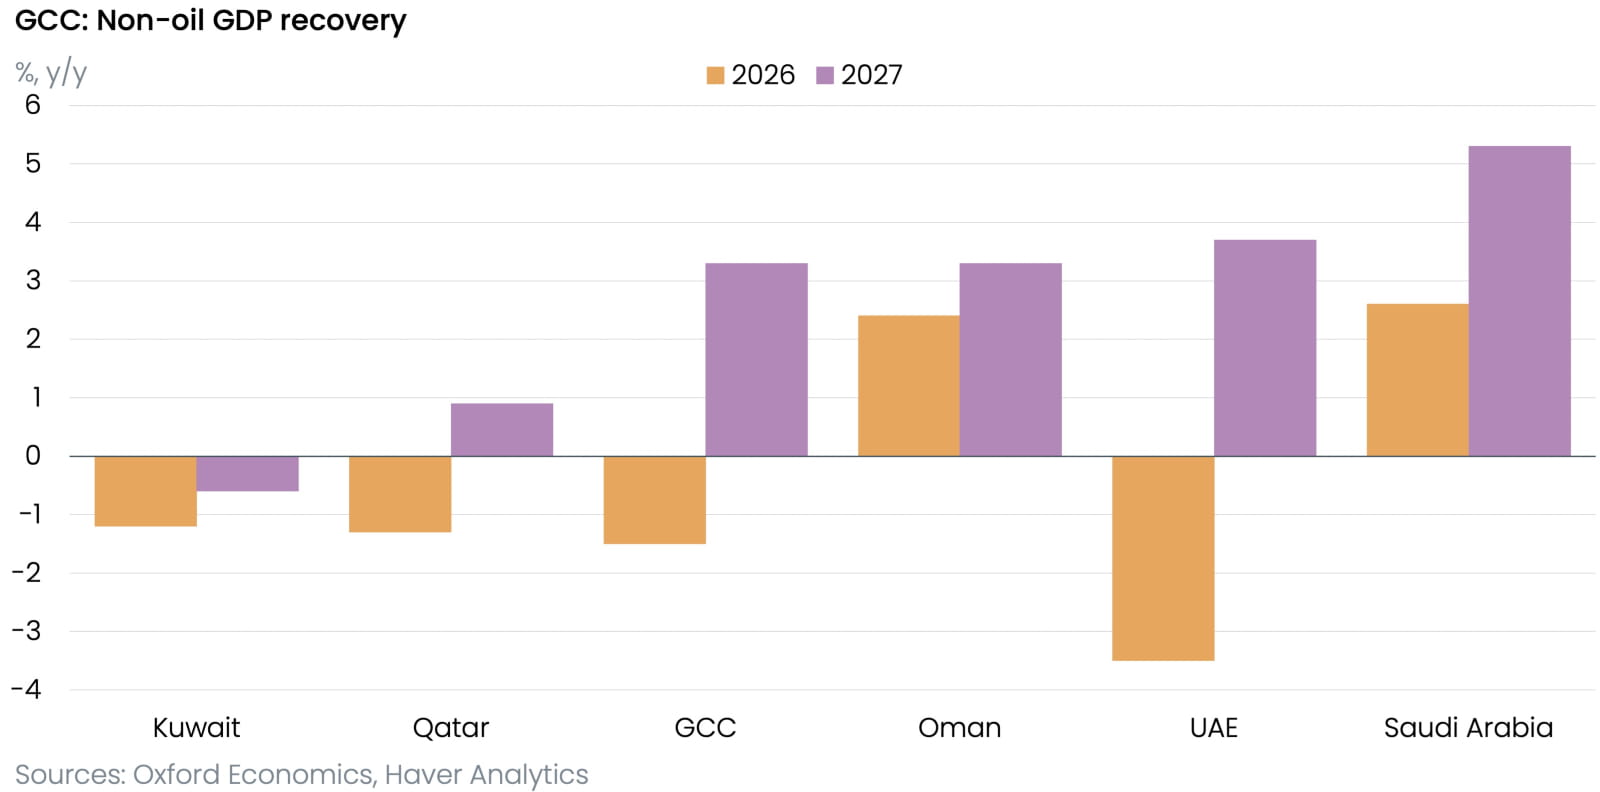
Available data confirm the severe hit to activity since the conflict began in February. Saudi Arabia's economy sharply contracted by 4.7% y/y in Q2 after growing by 3% in Q1. The slump was driven by a 24.8% contraction in oil activity, while non-oil activities expanded by 0.6%. Recent indicators suggest the non-oil private sector continues to expand, with the August PMI at 53.8, marking a six-month high. However, exports orders continue to decline highlighting the impact of regional tensions. We expect domestic demand to cushion the oil shock but not fully offset the drag from weaker exports. The PMIs for UAE and Kuwait also pointed to non-oil activity recovering despite lingering geopolitical uncertainty. Overall, we expect GCC non-energy sectors to expand by 3.3% in 2027, following a 1.5% contraction this year (we projected a 1.1% decline three months ago).
Travel and tourism are among the sectors most exposed to the disruption. We expect both to rebound strongly next year although a full recovery to pre-war levels is unlikely before 2028. In the UAE, where tourism contributes around 13% of GDP, we forecast visitor numbers to rebound by 30% in 2027 and a further 59% in 2028, following a projected drop of 46.7% this year. The risks to our sector forecast are currently tilted to the downside, as they do not fully incorporate the implications of the renewed hostilities, which will still likely affect demand 9-12 months ahead.
Firms have been cautious to ramp up hiring but anecdotal evidence does not point to a large or persistent exodus of workers or widespread labour shortages. Indeed, weakness in travel and tourism appears to have created substantial spare-capacity in labour intensive sectors such as hospitality and transport, limiting near-term wage pressures. Looking ahead, we expect labour demand to strengthen as GCC economies recover.
GCC governments will likely focus on reprioritising spending even as revenues recover next year and beyond and we expect security and economic diversification to command a growing share of government resources. Saudi Arabia will continue to reallocate capital towards projects with greater emphasis on areas such as education and healthcare that support improvements in living standards. More broadly, we expect GCC countries to accelerate efforts to diversify export routes and reduce their exposure to the Strait of Hormuz and Bab el-Mandeb. Several countries are already considering new pipeline capacity, although routes that bypass these chokepoints would, in practice, likely require access to export terminals on Oman’s Arabian Sea coast. Such projects will therefore entail substantial investment not only in pipelines but also in ports, storage and associated export infrastructure. Overall, we forecast GCC government spending growth will slow to 5.1% in 2027 from 7.5% in 2026, although this would still be stronger than the average pace of the past decade.
We expect GCC inflation to rise further in the coming months as supply chains remain disrupted but think pressures will subsequently ease, with inflation averaging 1.8% in 2027, down from a projected 2.2% this year. Food and beverage inflation has been the largest contributor to inflation across the GCC this year and is likely also the most visible source of price pressure for households. While price controls have helped contain increases in the cost of essential goods in supermarkets, prices for non-essential items, many of which are imported, have risen more rapidly. Qatar has seen the sharpest increase in food prices so far but the rise has not been confined to countries facing disruption, likely reflecting rises in shipping charges and insurance costs. With inflation set to ease next year, we expect the US Federal Reserve to ease policy modestly in H2 2027 and regional rate policies to follow suit.
The ongoing conflict continues to reshape the outlook for the broader Middle East as well. Iran’s ability to export oil has been severely curtailed by the US naval blockade, weighing on the outlook. Meanwhile, the UAE severed economic ties with Iran in August, closing a key economic lifeline for Iran. Thus, despite Iran’s resilience in the early months of the war, we forecast its GDP to contract by nearly 10% this year, before a shallow rebound in 2027. Iraq has been able to reroute some of its exports via Syria and Turkey, while advancing pipeline plans to increase future resilience. We forecast a sharp 20.8% rebound for the economy in 2027, following a projected 19.5% decline this year.
The wider conflict is also weighing on the outlook for Lebanon, where we forecast a contraction of nearly 7% this year. The outlook for Jordan is more resilient; although geopolitical headwinds have been a headwind to tourism and industry, we expect the economy to withstand these pressures with growth of 2.9% this year and 2.6% in 2027. In Syria, We project annual expansion in excess of 10% next year, supported by renewed investment, particularly in banking and energy, monetary reforms, and the gradual reopening of regional trade links.