Q3 2026: The ICAEW Economic Update Middle East, is a quarterly economic forecast for the region prepared directly for the finance profession.
Economic Update: Export recovery underpins a strong 2027 outlook
- Export recovery, particularly of energy, is set to drive a 5.8% rebound in GCC growth in 2027.
- Non-oil activity will also gain momentum, with consumers benefitting from improving confidence and easing pricing pressures.
- We project a substantial rebound in travel and tourism next year, though a full recovery is unlikely before 2028.
We expect the global economy to continue to weather the energy price shock resulting from the unresolved US conflict with Iran Global GDP is expected to grow by 2.8% in 2027, 0.3ppt less than we projected three months ago, albeit up from 2.5% this year.
Within the region, the past six months have seen an uneven cycle of escalation and de-escalation. Recent developments, notably disruptions at Red Sea ports and the impairment of Saudi oil exports caused by damage to the critical East-West pipeline, point to a material and potentially more persistent threat to regional energy supply. Our baseline assumes trade and energy flows will gradually build through 2027, albeit remaining below pre-war levels for quite some time.
On this basis, we forecast aggregate GDP growth of 5.3% for the Middle East in 2027, following an unparalleled 6.3% contraction this year (we projected a 4.1% contraction three months ago). Favourable base effects will mechanically boost next year’s growth rate but we also expect a substantial rebound in activity as this year’s disruption gradually unwinds.
These projections are consistent with our outlook for the GCC economies, which we expect will recover strongly next year after a dismal 2026. We forecast GCC GDP growth of 5.8% in 2027, following a 6.4% contraction this year (significantly deeper than the decline we projected previously). In Saudi Arabia, we project GDP growth to rebound by 4.7%, from a 4.6% contraction this year. The swing reflects primarily our expectation of gradual normalisation in the oil sector following disruptions this year. The UAE is set for a strong 2027, with growth forecast at 6.6%, more than reversing a 1.5% projected decline this year. Meanwhile we expect Qatar to record the region’s fastest expansion, at 11.5%, following a much weaker 2026. Qatar’s dependence on the Strait of Hormuz for energy exports has made it particularly vulnerable to the current disruption.
Chart 1: Real GDP growth
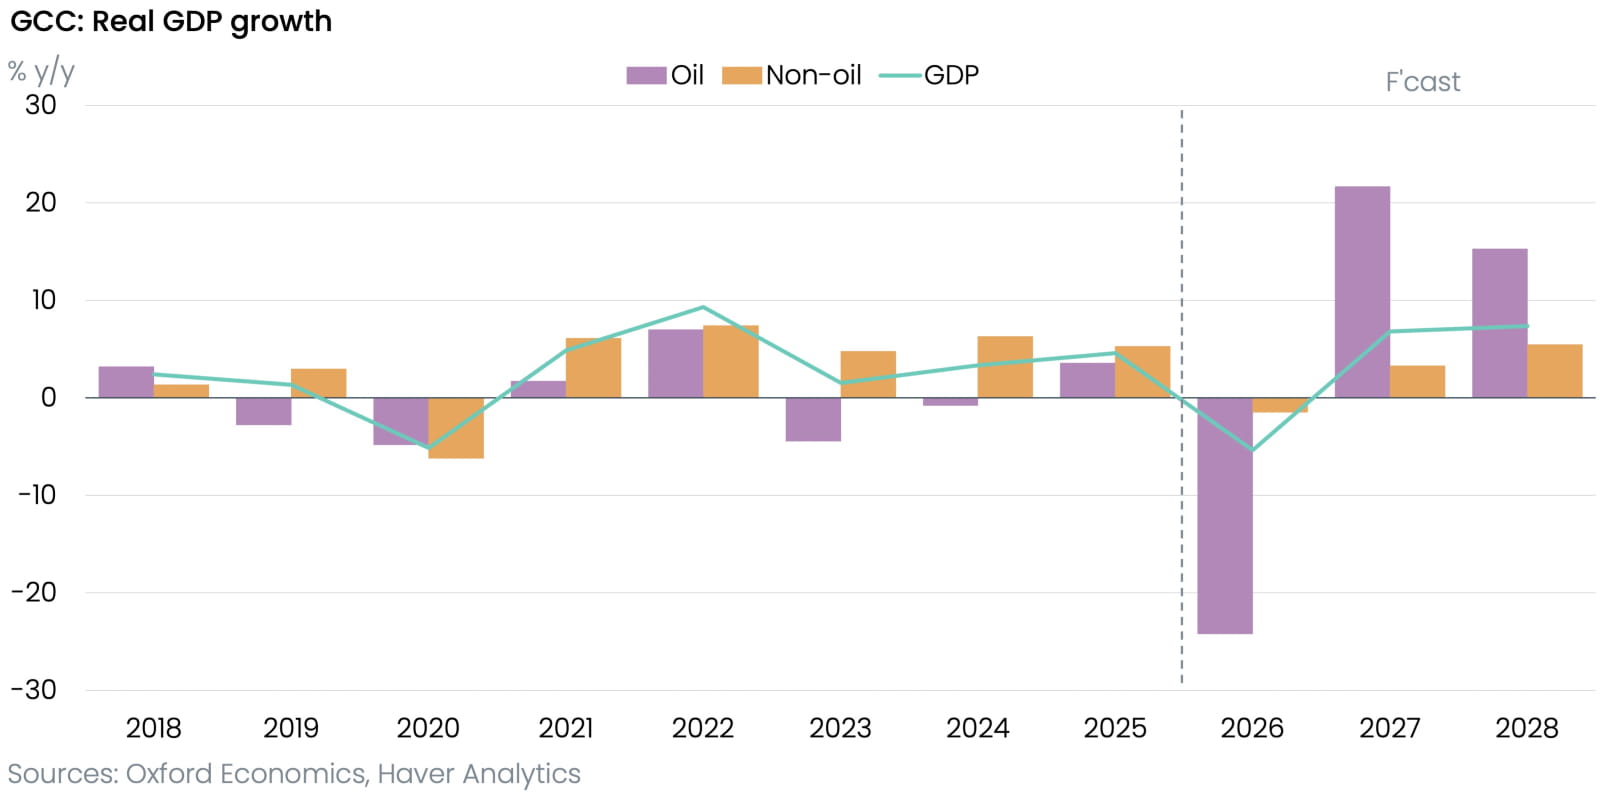
Our view of economic recovery in 2027 is heavily contingent on at least a partial normalisation of shipping flows through the key waterways. Overall, we forecast the GCC’s hydrocarbon sector will rebound with 25.9% growth in 2027, following a contraction of 26.9% this year.
Meanwhile, oil and gas prices have risen sharply in recent weeks in response to the escalation and disruption to Saudi oil exports. We expect tensions and prices to remain elevated, with Brent oil staying above US$100 per barrel until early 2027 and then dropping back slowly over the course of 2027-28.
Chart 2: Non-oil GDP recovery
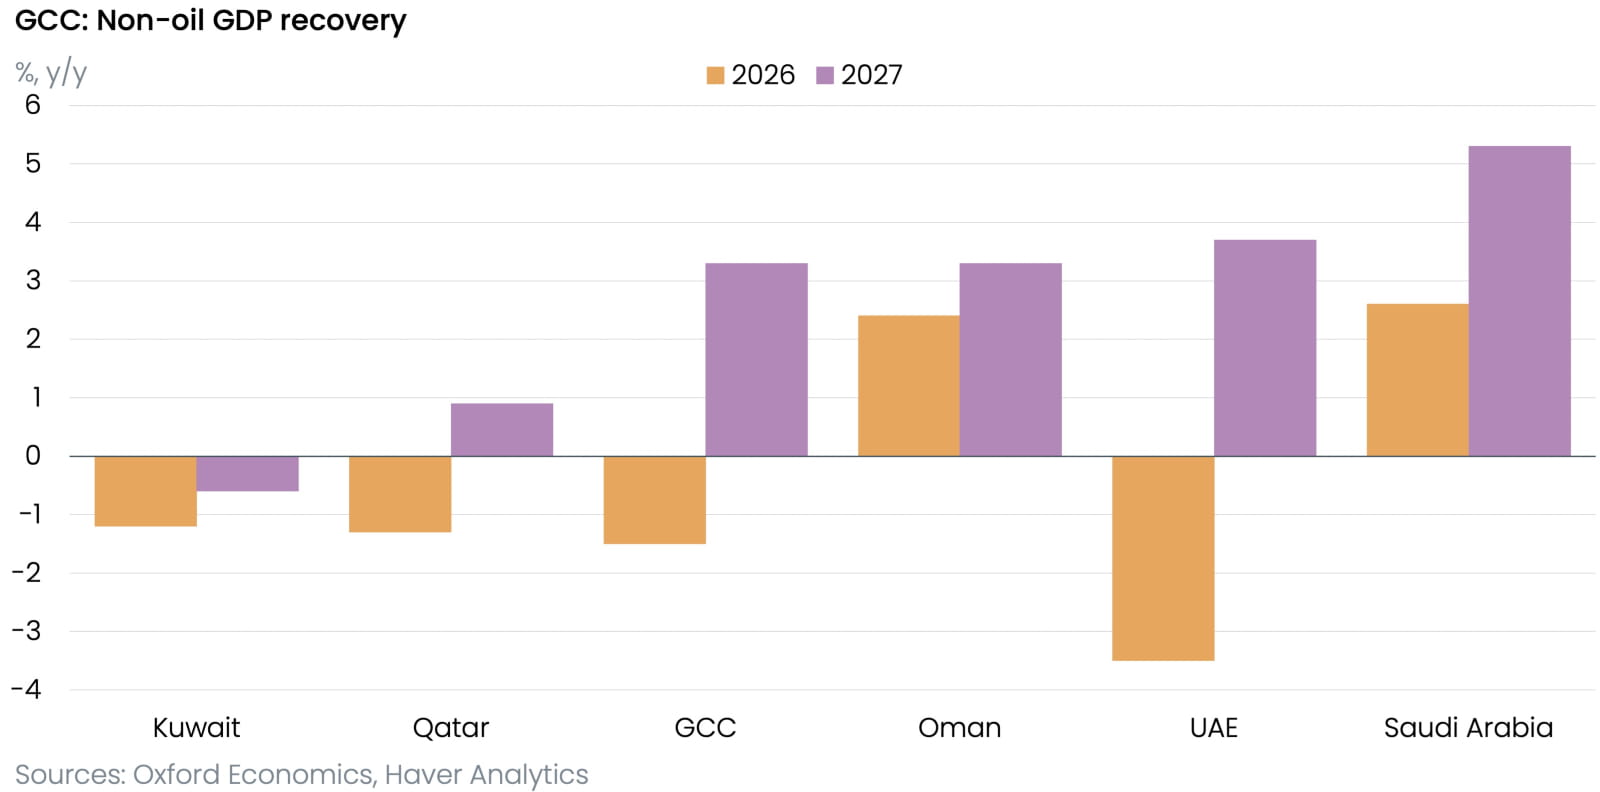
Available data confirm the severe hit to activity since the conflict began in February. Saudi Arabia's economy sharply contracted by 4.7% y/y in Q2 after growing by 3% in Q1. The slump was driven by a 24.8% contraction in oil activity, while non-oil activities expanded by 0.6%. Recent indicators suggest the non-oil private sector continues to expand, with the August PMI at 53.8, marking a six-month high. However, exports orders continue to decline highlighting the impact of regional tensions. We expect domestic demand to cushion the oil shock but not fully offset the drag from weaker exports. The PMIs for UAE and Kuwait also pointed to non-oil activity recovering despite lingering geopolitical uncertainty. Overall, we expect GCC non-energy sectors to expand by 3.3% in 2027, following a 1.9% contraction this year (we projected a 1.1% decline three months ago).
Travel and tourism are among the sectors most exposed to the disruption. We expect both to rebound strongly next year although a full recovery to pre-war levels is unlikely before 2028. In the UAE, where tourism contributes around 13% of GDP, we forecast visitor numbers to rebound by 30% in 2027 and a further 59% in 2028, following a projected drop of 46.7% this year. The risks to our sector forecast are currently tilted to the downside, as they do not fully incorporate the implications of the renewed hostilities, which will still likely affect demand 9-12 months ahead.
Firms have been cautious to ramp up hiring but anecdotal evidence does not point to a large or persistent exodus of workers or widespread labour shortages. Indeed, weakness in travel and tourism appears to have created substantial spare-capacity in labour intensive sectors such as hospitality and transport, limiting near-term wage pressures. Looking ahead, we expect labour demand to strengthen as GCC economies recover.
GCC governments will likely focus on reprioritising spending even as revenues recover next year and beyond and we expect security and economic diversification to command a growing share of government resources. Saudi Arabia will continue to reallocate capital towards projects with greater emphasis on areas such as education and healthcare that support improvements in living standards. More broadly, we expect GCC countries to accelerate efforts to diversify export routes and reduce their exposure to the Strait of Hormuz and Bab el-Mandeb. Several countries are already considering new pipeline capacity, although routes that bypass these chokepoints would, in practice, likely require access to export terminals on Oman’s Arabian Sea coast. Such projects will therefore entail substantial investment not only in pipelines but also in ports, storage and associated export infrastructure. Overall, we forecast GCC government spending growth will slow to 2.6% in 2027 from 7.4% in 2026, although it will likely pick up more strongly in 2028.
We expect GCC inflation to rise further in the coming months as supply chains remain disrupted but think pressures will subsequently ease, with inflation averaging 2.1% in 2027, down from a projected 2.5% this year. Food and beverage inflation has been the largest contributor to inflation across the GCC this year and is likely also the most visible source of price pressure for households. While price controls have helped contain increases in the cost of essential goods in supermarkets, prices for non-essential items, many of which are imported, have risen more rapidly. Qatar has seen the sharpest increase in food prices so far but the rise has not been confined to countries facing disruption, likely reflecting rises in shipping charges and insurance costs. Although regional inflation will ease next year, the US Federal Reserve seems unwilling to look through the inflationary effects of the ongoing energy price shock. We therefore expect another rate hike from the Fed in December and see GCC rate policies following suit. The higher rate path will keep regional borrowing costs elevated, with cuts pushed back to 2028.
The ongoing conflict continues to reshape the outlook for the broader Middle East as well. Iran’s ability to export oil has been severely curtailed by the US naval blockade, weighing on the outlook. Meanwhile, the UAE severed economic ties with Iran in August, closing a key economic lifeline for Iran. Thus, despite Iran’s resilience in the early months of the war, we forecast its GDP to contract by 11% this year, before a shallow recovery in 2027. Iraq has been able to reroute some of its exports via Syria and Turkey, while advancing pipeline plans to boost future resilience. We forecast a sharp 18.1% rebound for the economy in 2027, following a projected 20.8% decline this year.
The wider conflict is also weighing on the outlook for Lebanon, where we forecast a contraction of more than 7% this year. The outlook for Jordan is more resilient; although geopolitical headwinds have been a headwind to tourism and industry, we expect the economy to withstand these pressures with growth of 2.8% this year and 2.6% in 2027. In Syria, we project annual expansion in excess of 10% next year, supported by renewed investment, particularly in banking and energy, monetary reforms, and the gradual reopening of regional trade links.