Q3: Manufacturing & Engineering confidence returns to positive territory as exports strengthen.
- Business confidence in Manufacturing & Engineering rose to +8.0 from -13.7 in Q2, above the UK average and the sector's historical norm (+4.6).
- Domestic and export sales growth accelerated, with further gains expected, particularly for exports.
- Geopolitical risk remained the most widely cited growing challenge despite easing, while concerns about energy costs, labour costs and transport problems remained elevated.
- Annual salary growth was the fastest of any sector and companies expect pay to continue rising more quickly than the UK average next year.
- Input price inflation held steady but selling price growth eased, while profits growth picked up to match the UK average and is expected to strengthen further.
- Capital investment growth rebounded above the sector norm, though businesses plan more modest growth in both investment and R&D.
Business confidence in the Manufacturing & Engineering sector
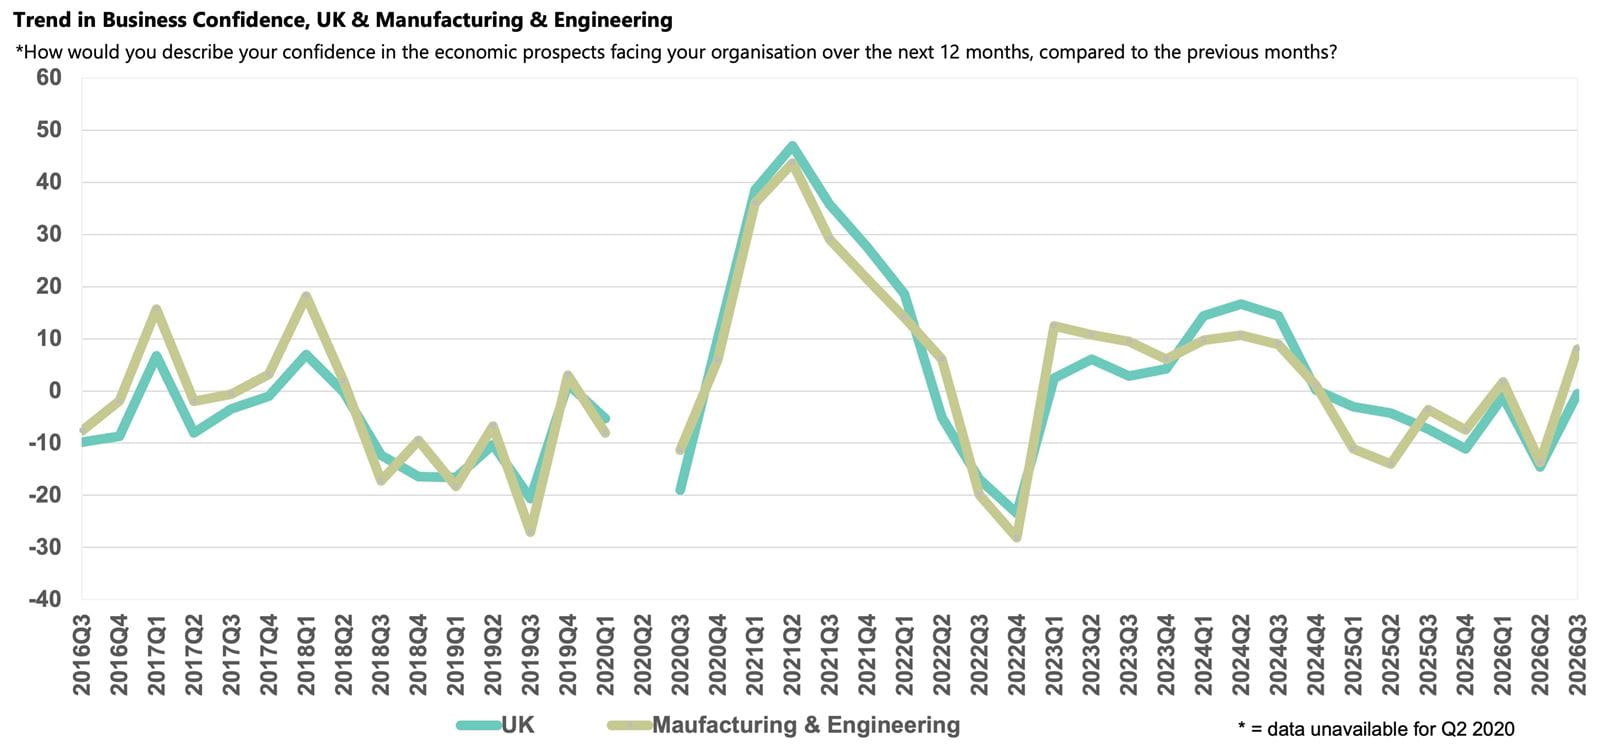
Business sentiment in Manufacturing & Engineering recovered strongly, with the Business Confidence Index rising from -13.7 in Q2 2026 to +8.0 in Q3 2026, the sector's highest score since Q3 2024. Sentiment is now well ahead of the UK average (-0.5) and above the sector's historical average (+4.6), with Manufacturing & Engineering the third most confident UK sector.
Strengthening exports growth helped to lift confidence, with businesses also optimistic about exports and domestic sales growth next year, though the ongoing US–Iran conflict continues to cloud the outlook and sentiment across the economy weakened towards the end of the survey period as renewed hostilities drove up oil and gas prices. The Bank of England Agents’ summary of business conditions for September 2026 reported that manufacturing output had stabilised and was slightly higher than a year earlier, but performance was variable across sub-sectors. Aerospace and defence continued to outperform, while housing-related manufacturing lagged and the automotive sector remained under pressure.
Exports and domestic sales growth
Annual exports growth in Manufacturing & Engineering picked up to 2.6% in Q3 2026, the sector’s strongest uptick since Q3 2023. Growth is now broadly in line with the UK average (2.8%) and just above the sector's historical norm (2.5%). Although developments in the Middle East will likely shape future trade prospects, companies anticipate a marked acceleration over the next 12 months to 4.9%, their most upbeat exports forecast since Q1 2018 and ahead of the projected UK rate (4.1%).
Annual domestic sales growth also strengthened to 2.6% in Q3 2026, climbing above the sector's historical norm (2.0%), though it underperformed the 3.6% rate recorded nationally. Businesses are more optimistic about the year ahead, projecting growth of 4.5%, slightly ahead of the 4.3% rise forecast nationally.
Business challenges
With the US–Iran conflict continuing through the survey period, geopolitical risk remained the most widely cited growing challenge in Manufacturing & Engineering, reported by 66% of businesses. While this share eased from 76% in Q2 2026, it remained above the national average (58%). Energy costs were cited as a growing challenge by 54% of companies, down from the previous quarter but still exceeding the national average (45%). Continued disruption to shipping and supply chains meant that 30% of businesses reported transport problems as a rising challenge, down from 37% in Q2 but well above both the sector norm (20%) and the UK average (18%).
Other challenges remain prominent in the sector, including labour costs (54%) and regulatory challenges (44%), while the tax burden at 41% was more than twice the sector's historical average (18%).
Despite improved sales performance, customer demand was cited as a rising challenge by 40% of businesses in the sector, slightly down from 42% in Q2 2026 and below the sector's historical norm (42%), though above the national average (36%). Concerns about competition in the marketplace rose to 37%, above the sector norm (34%).
Labour market
Employment growth in the Manufacturing & Engineering sector picked up modestly from a weak position, with businesses reporting annual expansion of 0.6% in Q3 2026. This was just below the UK average rise of 0.7% but slightly above the sector's historical norm (0.4%). Companies in the sector are more positive about recruitment over the next 12 months, predicting headcount growth of 2.0%, ahead of the UK projection (1.5%).
Annual salary growth accelerated to 3.3% in Q3 2026, this increase was the sharpest rise of any sector this quarter and well above both the UK average (2.8%) and the sector norm (2.2%). Companies expect wage pressures to persist, predicting they will raise pay by 3.0% next year, the highest projection of any UK sector and above the 2.6% rise forecast nationally.
Input and selling prices, and profits growth
Annual input price inflation in the Manufacturing & Engineering sector held at 4.0% in Q3 2026, marginally above the UK average (3.9%). Companies expect the rate to ease to 3.3% next year, though this is higher than the UK forecast at 2.9% and above the sector's historical norm (3.1%).
Businesses passed on less of their additional costs to customers in Q3 2026, with annual selling price growth slowing to 2.5%, though this still outpaced the 2.2% rate recorded nationally and the historical average (1.8%). Companies in the sector expect to raise prices by 2.8% over the next 12 months, a stronger outlook compared to the UK-wide projection (2.1%).
Stronger sales growth helped support profitability in the Manufacturing & Engineering sector. Businesses reported annual profits growth of 3.3% in Q3 2026, up from the previous quarter and the strongest since Q2 2024, matching the national rate and above the sector's historical norm (2.5%). Manufacturing & Engineering companies predict a further uplift to 5.6% over the next 12 months, expecting to outpace the UK average (4.5%).
Investment
Companies reported a sharp rebound in annual capital investment growth in Q3 2026, to 3.0%. This was the strongest growth in the Manufacturing & Engineering sector since Q1 2024, outpacing the rate recorded nationally (2.3%) and comfortably above the sector's historical average (1.7%). Despite this strong uplift, businesses remain wary about the year ahead, planning to bring growth back in line with the sector’s historical norm, to just 1.6%, and below the national projection (2.0%).
Annual R&D growth edged up to 2.3% in Q3 2026, matching the national rate and slightly exceeding the sector's historical norm (2.1%). Manufacturing & Engineering companies intend to ease growth over the next 12 months to 2.0%, broadly in line with the 1.9% rise expected across the UK.
UK results
The UK Business Confidence Index rebounded to -0.5, from -14.6 in Q2, but remained negative for a seventh consecutive quarter. Current sales and profits proved resilient, but firms downgraded their expectations for both over the next 12 months. Geopolitical risk remained the leading challenge, while elevated input and labour costs continued to put pressure on margins. Energy costs, regulations and the tax burden remain significant challenges. The rebound was broad but uneven: confidence rose in every sector, IT & Communications was the most positive, while Property and Construction remained deeply negative.
The latest quarterly findings are based on the period 13 July to 21 September 2026.