We set out the seven stages of business recovery, from growth and underperformance through to financial distress, crisis, stabilisation and recovery. We also explain the warning signs of financial difficulty, the options available to businesses and the role of insolvency practitioners (IPs).
What is insolvency?
Insolvency describes a situation when a company or individual can’t pay what they owe on time, or when the value of their assets is less than the money they owe. Financial difficulty does not necessarily mean that a company will enter a formal insolvency procedure. Depending on the circumstances, there may be opportunities to restructure the business, improve its financial position or agree arrangements with creditors.
An IP is a licensed professional who can advise on financial difficulties and, where appropriate, act in formal insolvency procedures. Not every conversation with an IP leads to insolvency. An IP may be involved before a formal process begins, including to assess the viability of a business and consider possible routes to recovery.
Recognising financial difficulty early
Decline and recovery curve, moving through seven broad stages. The important point is not simply where a business is on the curve, but whether those responsible for the business are recognising changes and taking action. The earlier a problem is identified, the more time there may be to understand its causes, consider different options and seek appropriate advice.
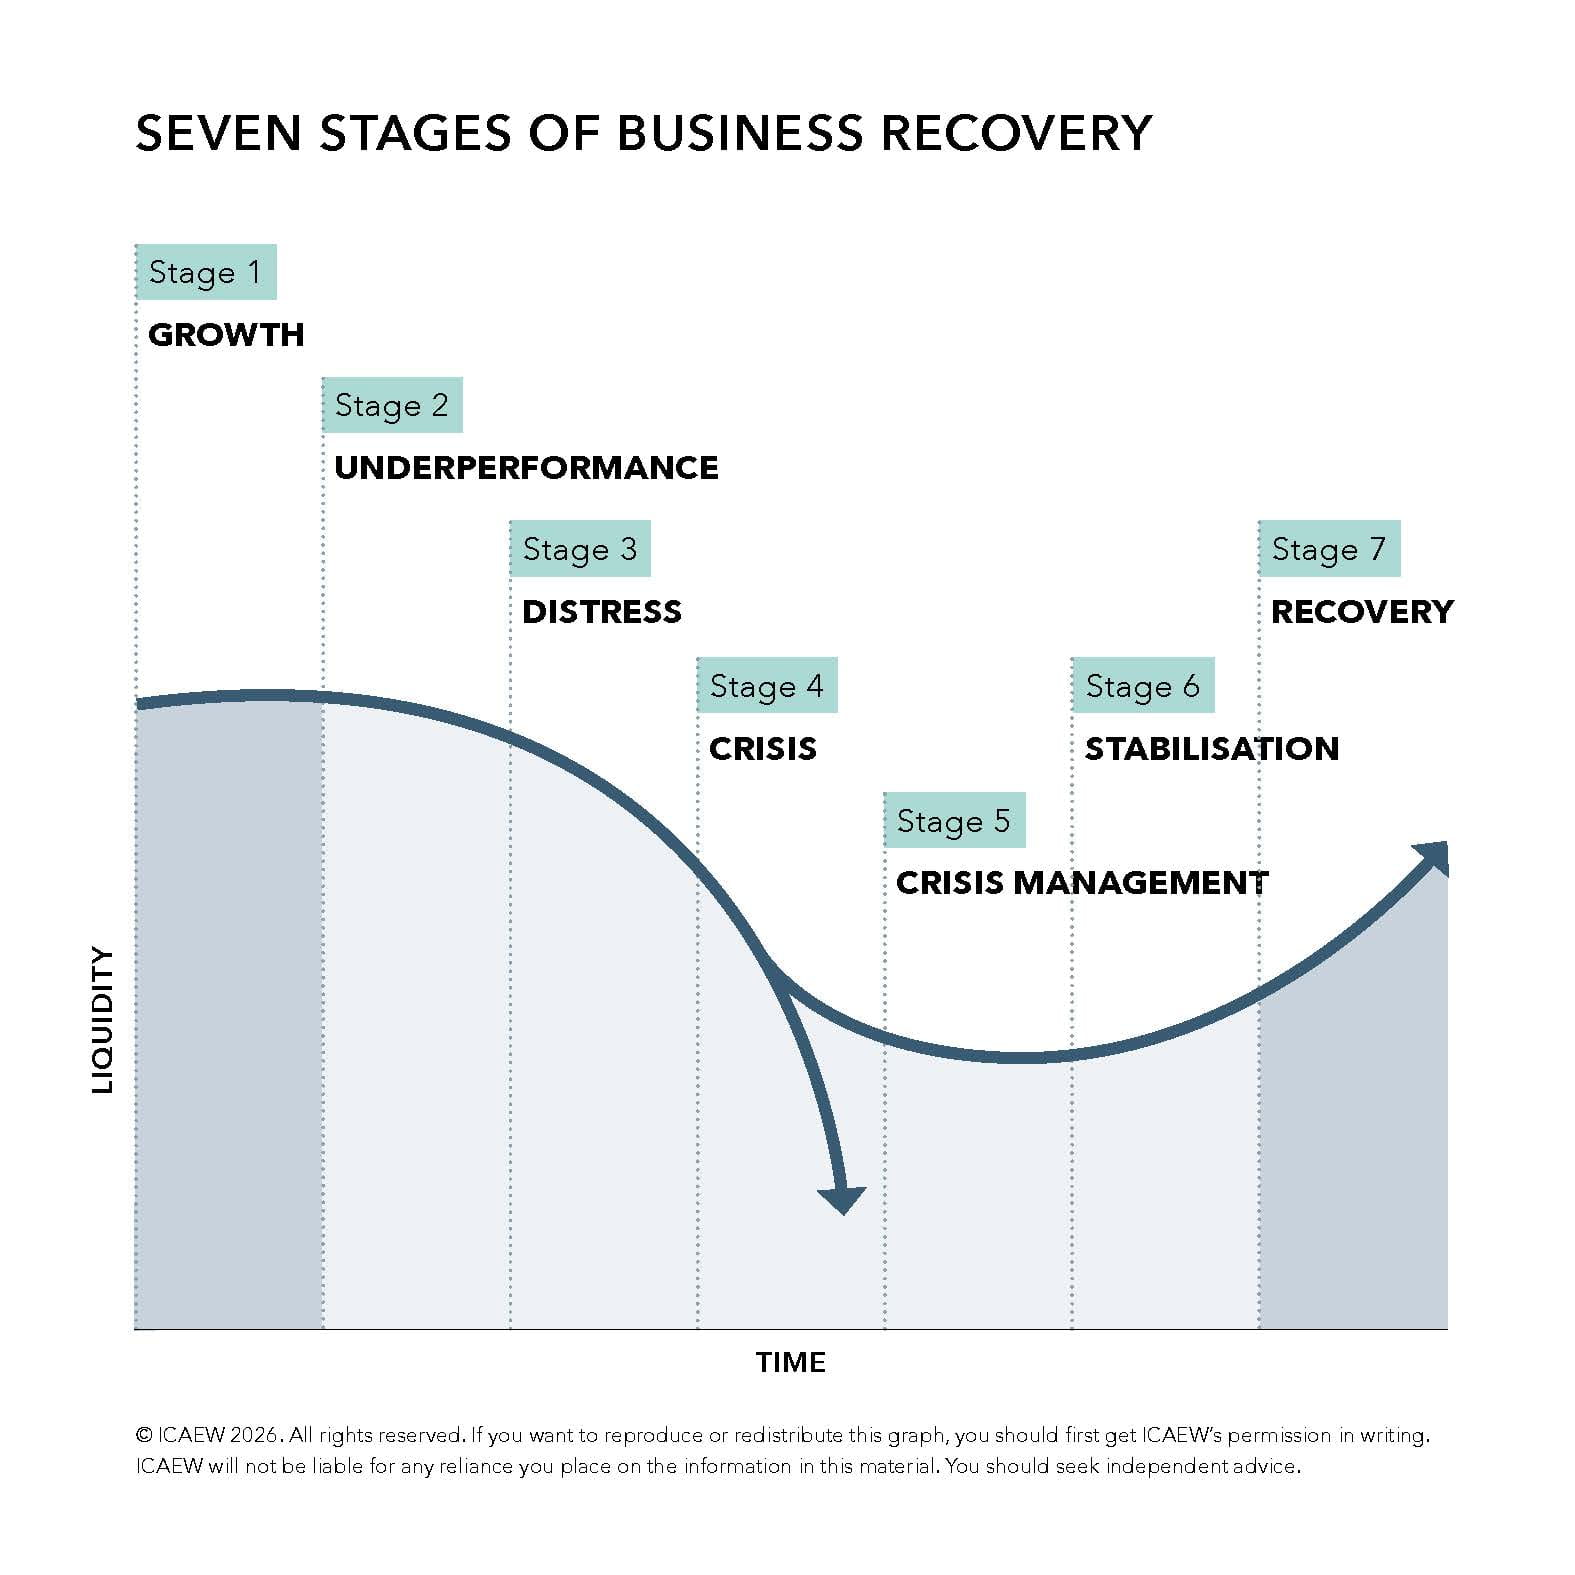
Stage 1: Growth
Can a business fail even when it's growing?
It may seem counterintuitive to think about failure during a period of growth. However, IPs often see increased demand during economic recoveries, when businesses that have survived difficult periods are suddenly inundated with orders.
Rapid growth can put pressure on cash flow. Businesses may need to pay suppliers and fulfil orders well before receiving payment from customers, creating liquidity problems even when sales are strong. Over-trading, currency fluctuations and poor payment terms can add to the pressure. The seeds of failure are often planted during good times. To manage growth sustainably, businesses need accurate, up-to-date management information and a clear understanding of their financial position.
A common mistake is over-trading, where a business takes orders without considering its cash flow. If suppliers demand money on terms worse than customers pay on, or there are delays being paid, each order can lead to a worse short-term position. The same can happen if currency fluctuations catch a business out and it loses money on each sale. If protections and measures aren’t taken against this, a business will get into difficulties while seeming to thrive.
In these cases the gap has to be plugged, through credit, quicker payment, or another type of financial injection, such as debt or investment.
Stage 2: Underperformance
How do I know if my business is starting to struggle?
Underperformance is frequently invisible on the surface. Unless there is a sudden and catastrophic disaster (a sudden loss of key staff, a new competitor with a better or cheaper product), it is possible for a business to trade apparently successfully while things go wrong under the surface.
Early warning signs include a lower bank balance than expected, unplanned use of an overdraft, and falling profit margins, usually because costs are rising faster than revenue. Rising interest rates compound this risk for indebted businesses, and owners often sense something is wrong before they can name it. The consistent advice at this stage: ask hard questions and act early. Liquidity problems rarely resolve on their own, and a licensed insolvency practitioner can help separate the underlying cause from its symptoms.
Stage 3: Distress
What should I do if my business is in financial distress?
Left unaddressed, underperformance can tip into distress, or what's sometimes called the "zone of insolvency." This is not yet a crisis, and it's far from certain the business will fail. But external advice becomes more likely to be necessary from here, and the earlier it's sought, the more options remain: more time, more assets, and more room to make the changes needed to turn things around.
Visiting an insolvency practitioner only once bills are already being missed narrows their options considerably. Consulting one sooner, while other paths are still open, keeps more of them available.
Stage 4: Crisis
What are my options if my business is facing a financial crisis?
A business that ignores distress will eventually reach crisis point, a lack of liquidity severe enough to threaten overheads, wages, tax and the basic running of the business. By this stage, both the owner's and the insolvency practitioner's options have narrowed, and some form of formal insolvency arrangement is likely, though not certain.
Even here, seeking help beats facing it alone: an experienced adviser brings clarity, distance and technical expertise the owner may not have at a moment of pressure. It's also worth noting that unregulated advisers must refer clients on to a licensed insolvency practitioner to implement any solution, which is why it makes sense to go directly to one.
Stage 5: Crisis management
How can I save a business that is at risk of insolvency?
When a business enters a crisis, there are usually several possible routes forward. An experienced insolvency practitioner can help directors assess whether the business has a realistic prospect of recovery and identify the most appropriate course of action.
In the short term, crisis management is often about reducing costs and maximising income. Simple measures can make an immediate difference, such as strengthening cost controls, requiring central approval for purchases, chasing outstanding debts and negotiating revised payment terms with creditors. Longer-term changes such as restructuring the business or removing loss-making product lines may also be needed. Where appropriate, an IP can advise on the formal insolvency options available and help manage the process.
At the point a company is technically insolvent, or there are doubts about its solvency, the directors’ duties change, with them having to act in the interest of creditors rather than shareholders.
Stage 6: Stabilisation
How can I stabilise a business after financial difficulties?
Having averted collapse, the focus shifts from survival to building a sustainable footing, sometimes with a new senior management team. But if crisis management is about making sure the business avoids imminent collapse, this stabilisation phase is about making sure any changes made and its operational approach create a sustainable model for all concerned parties.
A company that went through liquidation has no way back, but one that entered a company voluntary arrangement, or some pre-pack arrangements, may be able to return to normal trading as confidence and evidence of recovery build with creditors and lenders.
Stage 7: Recovery
How can I make sure my business stays financially healthy?
Recovery is the payoff for having acted early and honestly through the stages before it. The priority now is making sure the lessons of the crisis and stabilisation periods aren't lost in the rush back to business as usual. Unless it was a major one-off external event or an unfortunate string of events, it is highly likely the business owners or managers had some responsibility for its troubles and therefore sowed the seeds for their own downfall.
There may still need to be some continued input from a recovery or turnaround practitioner to work with the business owner to ensure new, better habits and new, more profitable approaches to business are carried on.
Corporate insolvency measures
Read four examples of measures that are frequently implemented in cases of corporate insolvency, from ICAEW's guidance on business recovery.

Frequently asked questions
-
What are the early warning signs of insolvency?
- Cash flow. A constant shortage of cash, beyond the periodic dips every business experiences.
- High interest payments. A sign lenders view the business as higher risk, or are demanding stronger personal guarantees.
- Defaulting on bills. An increasing frequency of missed payments, especially to HMRC or under formal arrangements.
- Extended debtor or creditor days. Delays either paying suppliers or collecting from customers, both of which can cascade into further cash flow problems.
- Falling margins. Profit, not turnover, is what sustains a business long-term — falling margins mean costs are too high or prices too low.
- Unhappiness. Distressed businesses are rarely happy ones; stressed decision-making, random cost-cutting and senior departures are often symptoms of a business further down the curve than owners realise.
-
Does meeting an insolvency practitioner mean my business will be liquidated?
No. Not every meeting with an IP leads to insolvency. IPs will always explore whether and how a business can be saved before any formal process is considered.
-
What's the difference between administration, a CVA, receivership and liquidation?
A CVA lets a company repay its debts, or a percentage of them, under an agreed arrangement with creditors. Administration allows an IP to try to rescue the company or sell its assets to repay creditors. Receivership recovers money owed to a secured creditor, such as a bank. Liquidation collects and sells a company's assets to pay creditors in a set order, and ends the company.
-
When should a business seek insolvency advice?
As early as possible. The earlier a business owner acts, the more options an insolvency practitioner has, and the more assets and time remain to turn the business around. It's very rare to act too early, but easy to leave it too late.
-
What should directors do if they are concerned about their company's solvency?
An experienced insolvency practitioner (IP) can help directors assess whether the business has a realistic prospect of recovery and identify the most appropriate course of action. The value of an IP is that, having faced this decision many times before, they are able to identify whether there is a realistic chance of survival, of the business recovering and succeeding over time.
How do I contact an ICAEW-licensed insolvency practitioner?
Search our directory for the specialisms of ‘restructuring’ or ‘insolvency’ to find an ICAEW-licensed practitioner.