Q3: Business sentiment in Scotland climbed out of negative territory in Q3 2026 and it is now the most optimistic region in the UK.
- The Business Confidence Index in Scotland rebounded to +9.5 in Q3 2026, from -21.1 in Q2 2026, moving into positive territory and above its historical norm of +5.7.
- Scotland is now the most optimistic of all UK regions and nations, significantly outperforming the UK average (-0.5).
- Domestic sales and exports strengthened in Q3 2026 despite the heightened global uncertainty, with businesses expecting further growth in the year ahead.
- Labour costs remained the leading challenge, with geopolitical risks, energy costs and regulatory requirements also significant concerns.
- Input and selling price inflation eased as profits grew strongly, although geopolitical developments could impact the inflation outlook.
- Employment contracted while salaries rose sharply, but businesses expect modest job creation and slower wage growth over the next 12 months.
- Capital investment slowed compared to the previous quarter, though businesses anticipate a strong recovery and sustained R&D growth in the year ahead.
Business confidence in Scotland
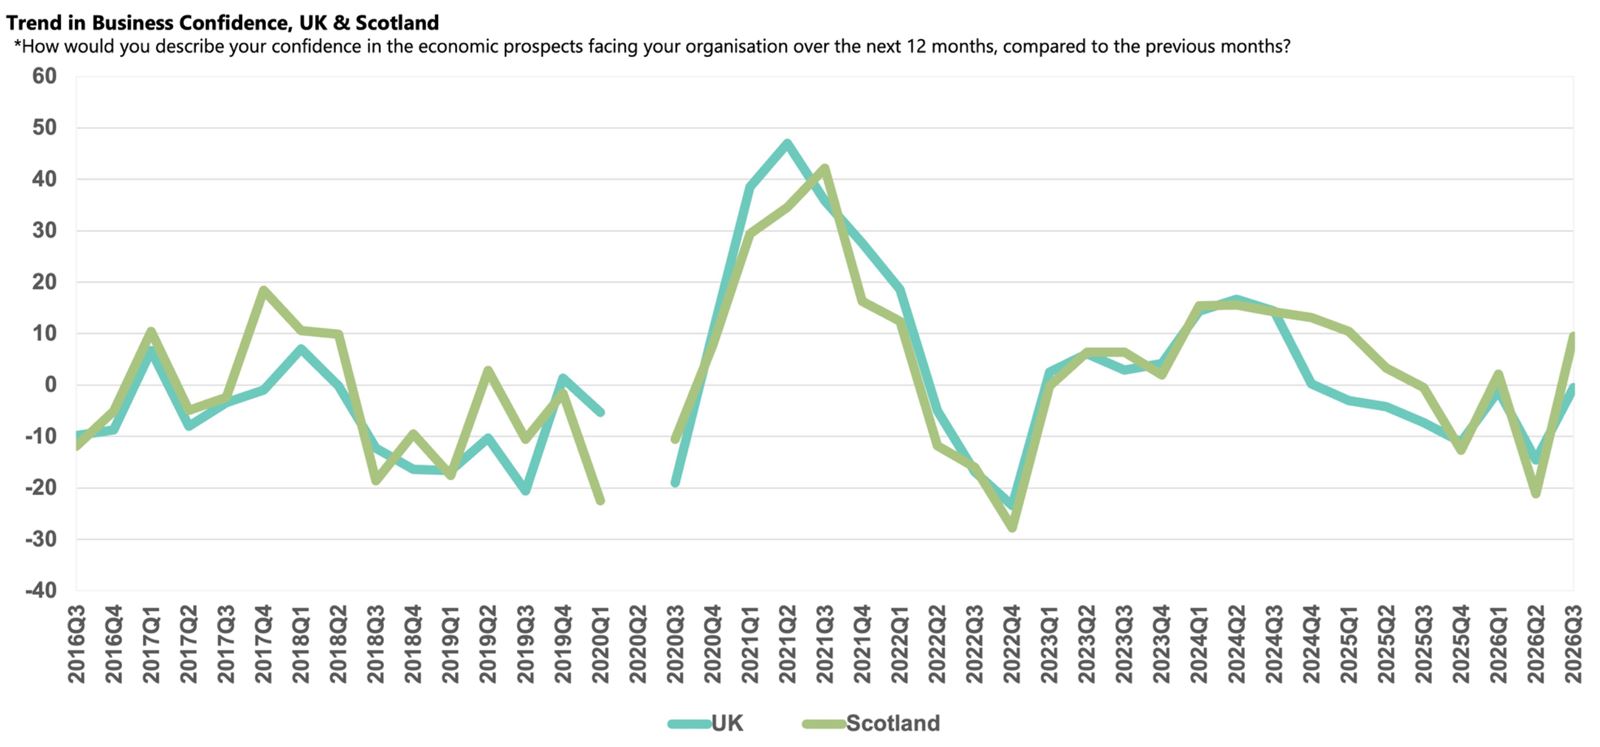
Sentiment in Scotland increased sharply in Q3 2026, with the Business Confidence Index returning to positive territory, rising from -21.1 in the previous quarter to +9.5. Confidence among Scottish companies was above both the historical norm (+5.7) and the UK average (-0.5).
Despite the heightened global uncertainty caused by escalation in the conflict between the US-Israel and Iran, and the subsequent closure of the Strait of Hormuz, there is a picture of “cautious optimism” among Scottish businesses. Businesses in the region reported resilient domestic sales and exports across the quarter, supporting a sharp expansion in profits. This strong performance is expected to continue over the coming year, with substantial increases in capital investment and R&D also anticipated. The optimism has been supported by Scotland’s strong economic growth in the second quarter of 2026, with GDP growth expanding by 0.7%, outpacing the 0.4% growth recorded in the UK over the same period.
Domestic sales and exports growth
Annual domestic sales growth increased to 3.6% in Q3 2026, rising above Scotland’s historical norm (3.0%) and matching the national average. Scottish businesses are among the most optimistic in the UK in their outlook and expect domestic sales growth to improve to 5.1%, markedly above the UK-wide projection of 4.3%. The robust performance and outlook for domestic sales in the locally important Banking, Finance & Insurance sector likely underpin the resilient sales outlook for Scottish companies.
Despite significant geopolitical risks and uncertainty, Scottish businesses reported resilient external trade in Q3 2026, with annual exports growth increasing slightly to 3.0%, marginally exceeding both its historical norm (2.9%) and the national average (2.8%). Companies are optimistic that exports growth will improve further over the coming year and predict a rise of 5.0% in the year ahead, outpacing the 4.1% rise anticipated for the UK as a whole.
Business challenges
Companies appear to still be struggling to absorb the higher costs related to the increases in employers’ National Insurance Contributions and successive rises in the National Minimum Wage. Labour costs were the most prominent challenge among Scottish businesses in Q3 2026, with 55% of companies surveyed citing them as a growing concern, marginally above the UK average of 53%.
Prolonged disruption caused by the war in the Middle East remained one of the key challenges for Scottish companies in Q3 2026, though concern eased slightly from the previous quarter. Geopolitical risk was the second-most frequently cited concern, reported by 52% of businesses and below the UK average of 58%. Worries about energy costs also declined but remained prominent, with 40% of the businesses surveyed identifying them as a growing challenge.
Regulatory requirements remain a prominent concern, with 46% of businesses in Scotland identifying the issue as a growing challenge, while anecdotal evidence indicates that some companies have been forced to scale back or abandon projects because of lengthy planning or consenting delays. This proportion matched the UK average and was marginally above the Scottish historical norm of 44%.
Input and selling prices, and profits growth
After rising in the two previous quarters, annual input price inflation among Scottish companies softened in Q3 2026, to 3.7%. This was the joint-lowest rise in the UK, lagging the UK average increase of 3.9%. Businesses expect further moderation over the coming year, but while the projected rise of 2.9% matches the growth projected nationally, this increase is above the region’s historical norm of 2.7%. The continued closure of the Strait of Hormuz poses a significant upside risk to this outlook.
The BCM indicated that Scottish companies are absorbing some input cost increases rather than passing them on to customers. Annual selling price growth slowed to 2.1% in Q3 2026, slightly below the UK average of 2.2%, but above the historical norm of 1.6%. Over the next 12 months, Scottish businesses expect to raise prices by 2.3%, exceeding the national forecast of 2.1%.
Stronger domestic sales and exports growth, alongside easing inflationary pressures, helped Scottish companies achieve profits growth of 5.9% in the year to Q3 2026. This was the strongest expansion since Q1 2023 and sharper than the UK average of 3.3%. With sales growth expected to strengthen further and inflationary pressures to ease, Scottish businesses reported the strongest profit growth forecast of any other part of the UK. They expect profits to rise by 7.2% over the next 12 months, well above the UK forecast of 4.5%.
However, with the majority of responses gathered before the renewed US/Israel-Iran hostilities in September, which has impacted fuel prices and heightened geopolitical uncertainty, these expectations could be revised in the near term.
Labour market
Scotland was the only part of the UK to reduce staff count in the year to Q3 2026, with companies in the region reporting a 1.3% decline in employment. This was the lowest increase since Q4 2020, but recruitment was at that time distorted by the Covid-19 pandemic. Excluding that period, jobs growth in Q3 2026 was the weakest recorded in BCM since Q2 2010, in the aftermath of the global financial crisis. While Scottish businesses expect employment to return to growth in the coming year, the forecast rise of 0.9% is among the weakest projections in the UK and lower than the historical average (1.2%).
Despite the fall in employment, Scottish companies reported one of the strongest increases in salaries of any UK region and nation in the year to Q3 2026 at 3.4% and was notably above the 2.8% rise recorded across the UK. Looking ahead, businesses plan to reduce annual wage growth to 2.2% over the next 12 months, bringing wage inflation in line with the historical norm and below the 2.6% rise projected for the UK.
Capital investment and R&D
Annual capital investment growth in Scotland slowed to 1.5% in Q3 2026, falling below the historical norm of 2.1%. Anecdotal evidence suggests that delays in securing planning approval or consent have forced some businesses to postpone or cancel projects over the preceding 12 months. However, Scottish businesses remained optimistic about the year ahead, expecting investment to rise by 4.6%. This was the strongest forecast increase of any UK region and nation and more than double the UK average of 2.0%. The positive outlook may reflect the transition towards net zero, with similarly strong investment growth expected in the Energy, Water & Mining sector.
Annual R&D growth in Scotland accelerated in Q3 2026, reaching its highest rate since Q1 2018, at 4.1%. This uplift was more than double the region's historical norm (2.0%) and the sharpest rise of any other part of the UK. Businesses expect this strong R&D growth to continue over the coming year and forecast a slight acceleration, to 4.3%, which is the sharpest increase predicted in the UK and more than double the national projection of 1.9%.
UK results
The UK Business Confidence Index rebounded to -0.5, from -14.6 in Q2, but remained negative for a seventh consecutive quarter. Current sales and profits proved resilient, but firms downgraded their expectations for both over the next 12 months. Geopolitical risk remained the leading challenge, while elevated input and labour costs continued to put pressure on margins. Energy costs, regulations and the tax burden remain significant challenges. The rebound was broad but uneven: confidence rose in every sector, IT & Communications was the most positive, while Property and Construction remained deeply negative.
The latest quarterly findings are based on the period 13 July to 21 September 2026.