Q3: Business confidence in Wales returns to positive territory, reaching its highest level in two years.
- Business confidence in Wales rose sharply in Q3 2026, increasing from -14.1 in Q2 2026 to +7.8, surpassing both the historical norm (+2.6) and the UK average (-0.5).
- Domestic sales strengthened, but expectations remain subdued. Export growth weakened amid global disruption, although businesses anticipate a recovery despite continued risks.
- Regulatory requirements was the leading challenge facing Welsh businesses, with geopolitical risk and the tax burden also significant concerns.
- Employment and wage growth slowed as hiring costs increased, but skills shortages and high staff turnover continued to create pressure on recruitment.
- Supply chain disruption and higher energy costs pushed up input and selling prices, and while profits growth improved, businesses expect momentum to weaken.
- Capital investment growth marginally outpaced the historical norm and businesses expect a marked acceleration in R&D spending in the year ahead.
Business confidence in Wales
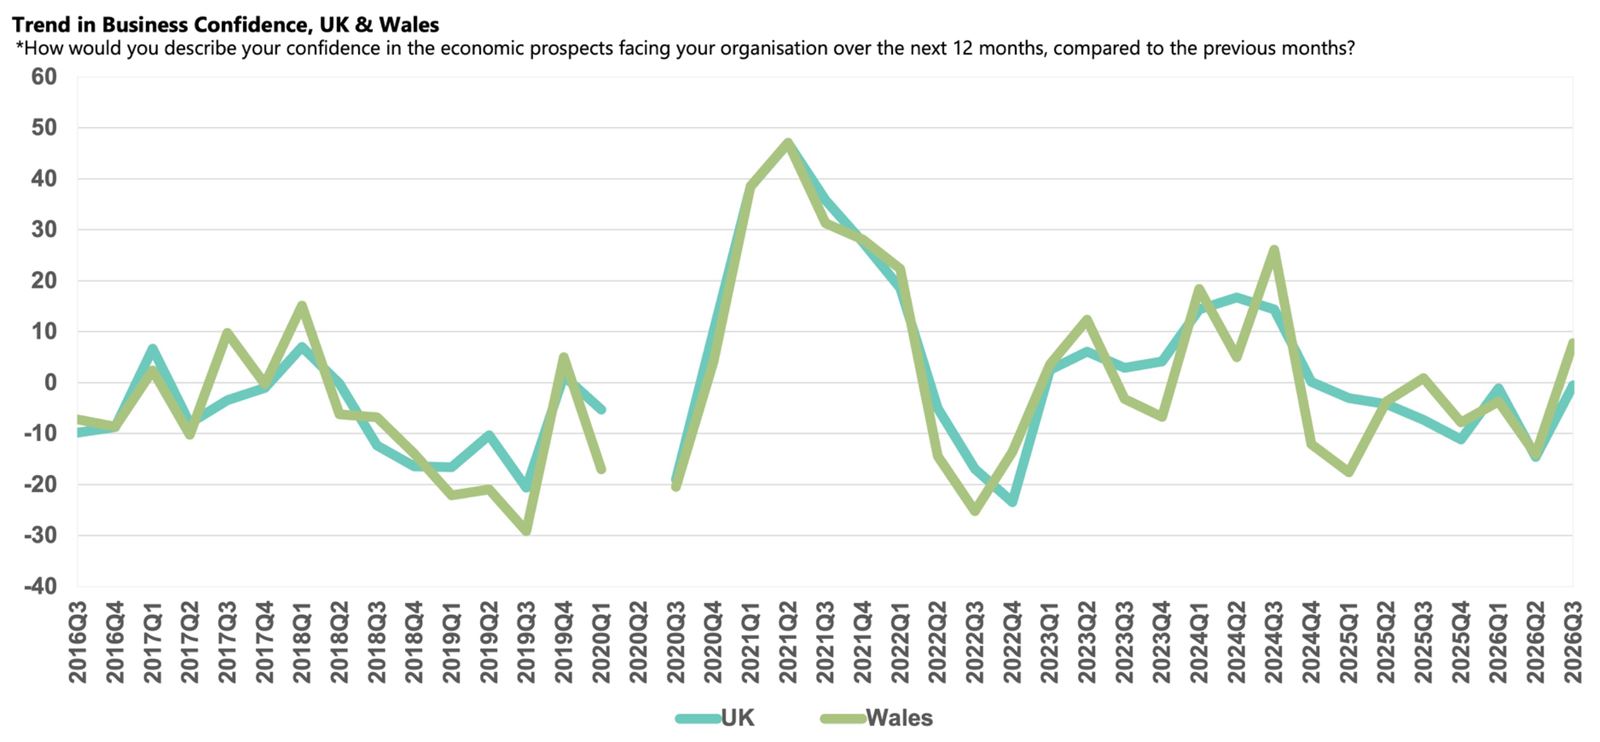
Sentiment in Wales climbed out of negative territory in Q3 2026, with the Business Confidence Index rising from -14.1 in Q2 2026 to +7.8. This marked the region’s highest score since Q3 2024, with Welsh businesses among the most confident in the UK, behind only Scotland (+9.5). The figure was also above both the UK average (-0.5) and the nation’s historical norm (+2.6).
The election of a new Plaid Cymru Government has likely been a key contributor to the uplift in confidence. However, like the rest of the UK, the protracted US-Israel war with Iran and disruption in the Strait of Hormuz continues to drive up wholesale oil and gas prices, increasing input costs and fueling uncertainty for Welsh businesses.
Domestic sales and exports growth
Companies in Wales reported that annual domestic sales growth improved in Q3 2026, reaching its highest rate since Q2 2024, at 3.6%. However, while most UK nations and regions expect domestic sales growth to increase further over the next 12 months, companies in Wales expect domestic sales growth to drop back below the historical norm (3.0%), to 2.7% over the coming year, the weakest outlook of any UK region.
Welsh businesses reported that exports growth slowed significantly from the previous quarter, dropping to 2.1% in the year to Q3 2026. This modest growth underperformed both the national average and its historical norm (both 2.8%). It is undoubtably linked to weaker external demand, as the prolonged closure of the Strait of Hormuz continues to disrupt international trade. However, businesses remain optimistic that exports sales will improve in the near term, and anticipate a 4.2% uplift over the coming year, broadly in line with the 4.1% rise projected across the UK. The volatile global trading conditions remain the key downside risk to this outlook. With Brent crude oil exceeding $100 per barrel in the final weeks of the survey period, transport costs are likely to increase in the short term, potentially affecting the outlook.
Business challenges
Regulatory requirements were the most prominent challenge for businesses in Wales in Q3 2026. The proportion of businesses citing this issue climbed to a new survey record high of 66%, with these concerns more prevalent among Welsh businesses than in any other UK region or nation. At least part of this uptick in concern can be attributed to the passing of the Employment Rights Bill and the Renters’ Reform Act passed earlier in the year.
Labour costs also remained a prevalent concern for companies in Wales in Q3 2026, with the uplift in employers’ National Insurance Contributions and consecutive increases in the National Minimum Wage in recent years still the key contributors. This challenge was reported by 60% of the businesses surveyed in Wales as a growing challenge, marginally above the national average (58%).
The continued disruption caused by the war in the Middle East is reflected in the proportion of Welsh businesses reporting geopolitical risk as a growing concern in Q3 2026. Geopolitical risk was the third-most prevalent rising challenge, with the proportion increasing from the previous quarter to 59%, broadly in line with the national average of 58%. Meanwhile, at nearly three times the historical average (17%), 54% of businesses cited the tax burden as a growing issue in the year to Q3 2026, which again was more prevalent than in any other region.
Labour market
Anecdotal evidence from ICAEW members in Wales suggests that the uplifts in employers’ National Insurance Contributions and the National Minimum Wage continue to pose a significant challenge for businesses. Consequently, employment growth among Welsh businesses slowed to just 0.3% in the 12 months to Q3 2026, less than half the national growth rate (0.7%) and a quarter of the historical average (1.2%). While businesses in Wales expect to increase headcount at a sharper rate over the coming year, the projected rise of 1.3% is below the 1.5% increase forecast for the UK.
Despite subdued employment growth, recruitment pressures remain. Concerns about the availability of management skills (20%) and staff turnover (35%) were more prevalent in Wales than in any other UK region or nation, with the latter reaching a three-year high at nearly double its historical average of 19%.
The drop-off in employment growth in the year to Q3 2026 is reflected in annual wage inflation slowing to 2.4% in the year to Q3 2026. This rise was the lowest rate since Q3 2021 and lagged all other UK regions. Companies in Wales anticipate that wage growth will moderate further over the next 12 months, to 2.2%, and while this is marginally ahead of the Welsh historical norm (2.1%), it remains one of the weakest projections in the UK.
Input and selling prices, and profits growth
The uptick in oil and gas prices and supply chain bottlenecks caused by the prolonged closure of the Strait of Hormuz have started to feed through to businesses’ operating costs, with Welsh businesses reporting that input prices rose by 4.5% in the year to Q3 2026. This was significantly above the 3.9% increase recorded nationally and above all other parts of the UK. While companies in the region expect inflationary pressures to soften to 3.6% over the coming year, this is markedly above both the region’s historical norm (2.8%) and the national average forecast (2.9%).
Welsh businesses continue to pass on some of their higher costs to customers. Companies reported they raised the selling prices by 2.5%, exceeding the 2.2% rise recorded across the UK. Businesses plan to soften selling price growth over the coming year, with the projected increase of 2.1% matching the national average forecast. However, this rise is still above the region’s historical norm of 1.6%.
Improved domestic sales growth in the year to Q2 2026, alongside slower wage inflation cost pressures, resulted in businesses in Wales recording an increase in profits growth to 4.1% in the year to Q3 2026. This uplift was among the strongest in the UK, outpacing the national average increase of 3.3%. Unlike most other UK regions and nations, businesses in Wales expect profits growth to moderate over the next 12 months. And while the projected increase of 3.3% is above the region’s historical norm (2.6%), it is the weakest forecast in the UK, and much lower than the UK projection (4.5%).
Capital investment and R&D
Welsh companies lifted their annual capital investment growth to 2.0% in the year to Q3 2026. This was slightly above its historical average of 1.9% but still among the weakest increases across the UK and below the national average of 2.3%. Businesses expect capital expenditure to grow at the same pace over the coming year, in line with the national outlook.
Annual R&D budget growth in Wales slowed sharply to 2.0% in Q3 2026, slightly below the UK average of 2.3%. However, companies expect growth to accelerate to 3.1% over the next 12 months. This would be nearly double the region’s historical average of 1.7%, marking the second-strongest projected increase in the UK, behind only Scotland at 4.3%.
UK results
The UK Business Confidence Index rebounded to -0.5, from -14.6 in Q2, but remained negative for a seventh consecutive quarter. Current sales and profits proved resilient, but firms downgraded their expectations for both over the next 12 months. Geopolitical risk remained the leading challenge, while elevated input and labour costs continued to put pressure on margins. Energy costs, regulations and the tax burden remain significant challenges. The rebound was broad but uneven: confidence rose in every sector, IT & Communications was the most positive, while Property and Construction remained deeply negative.
The latest quarterly findings are based on the period 13 July to 21 September 2026.