Q3: Business confidence in the West Midlands returns to positive territory as companies anticipate a strong rebound in exports growth.
- Business confidence in the West Midlands rose to +5.7 from -14.7 in Q2 2026, ahead of both the UK average (-0.5) and the region's historical norm (+3.9).
- Annual domestic sales and exports growth both picked up, and companies expect exports growth to accelerate markedly over the coming year.
- Geopolitical risk remained the most widely cited growing challenge, followed by labour costs, with both reported more widely than across the UK.
- Employment growth eased and lagged the historical norm, while salary growth picked up and is expected to remain above the norm over the next 12 months.
- Input price and selling price inflation both remained well above their norms, while companies expect profits growth to strengthen markedly.
- Businesses plan to slow capital investment growth, while R&D growth is set to remain below the national rate.
Business confidence in West Midlands
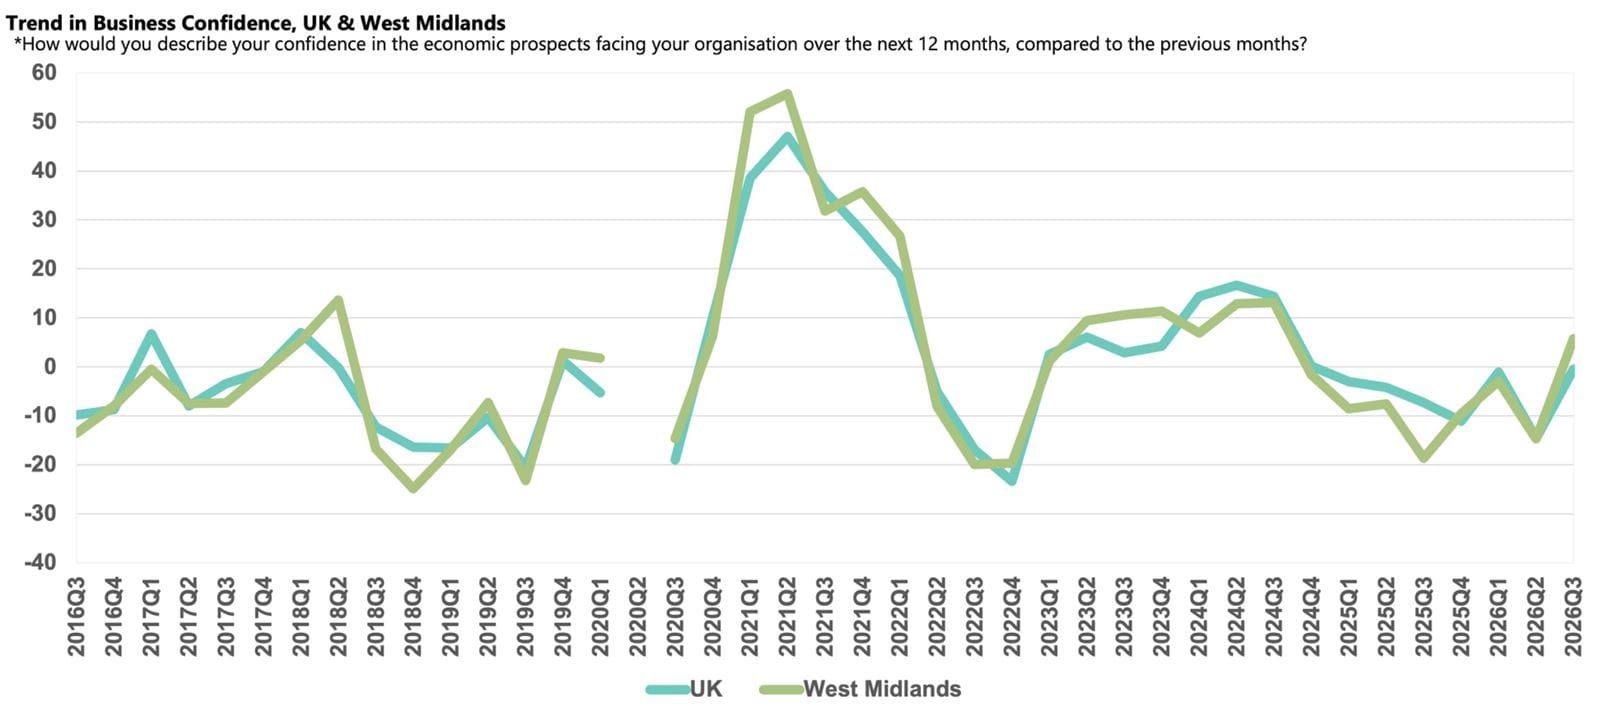
Business sentiment in the West Midlands improved sharply in Q3 2026, with the Business Confidence Index rising from -14.7 in Q2 2026 to +5.7. This was the region's highest score since Q3 2024 and returned confidence to positive territory, with businesses in the West Midlands among the most upbeat in the UK. The score was well ahead of the national average (-0.5) and moved above the region's historical average (+3.9).
The improvement reflected the resilience of the UK economy to the disruption caused by the ongoing US-Iran conflict. Businesses in the region reported uplifts in annual domestic sales and exports growth in Q3 2026 compared to the previous quarter and are particularly upbeat about the exports outlook. As a region with a large concentration of manufacturers and exporters, the West Midlands is likely to have benefited from the improvement in sentiment in Manufacturing & Engineering nationally, where confidence moved into positive territory (+8.0) for the first time since Q4 2024 on the back of strengthening exports growth.
However, businesses in the region continue to face significant headwinds. Geopolitical risk and labour costs were both more widely reported than across the UK as a whole, and national sentiment weakened towards the end of the survey period in September as renewed US-Iran hostilities drove up oil and gas prices.
Domestic sales and exports growth
Businesses in the West Midlands reported that annual domestic sales growth picked up to 3.8% in Q3 2026, the highest rate since Q4 2025. This was above both the region's historical norm (3.1%) and the UK average (3.6%). Companies expect growth to rise to 4.5% over the next 12 months, slightly ahead of the 4.3% increase forecast across the UK.
Annual exports growth also picked up to 2.3% in Q3 2026, although it remained below both the region's historical norm (2.5%) and the 2.8% national rate. Businesses are markedly more optimistic about the year ahead, expecting exports growth to accelerate to 5.3%, the strongest expected rate since Q3 2022. The view is among the most upbeat forecasts in the UK and exceeds the 4.1% rise predicted nationally. However, given the ongoing disruption in the Strait of Hormuz, this outlook is subject to considerable risks.
Business challenges
With US-Iran tensions continuing throughout the survey period, geopolitical risk remained the most widely cited growing challenge in the West Midlands, reported by 70% of businesses. This was broadly unchanged from the previous quarter and the highest share of any UK nation or region, and well above the UK average (58%). Energy costs were cited by 44% of companies, easing from last quarter and in line with the UK average (45%), although the survey may not fully capture the spike in wholesale gas and crude oil prices in September. Likely also linked to global events, transport problems were reported by 28% of businesses, above both the region's historical norm (16%) and the 18% recorded nationally.
Companies in the region continue to contend with domestic challenges too, including labour costs, regulations and taxes. Labour costs were reported by 67% of businesses, rising from last quarter and notably above the national average (53%), while regulations were cited by 49% of companies, up from the previous quarter and above the UK average (46%). While fading in prominence, the tax burden was reported by 39% of businesses, around twice the region's historical norm (19%).
Reflecting the prevalence of both global and domestic uncertainty, concerns about customer demand also edged up to 48%, well above both the region's historical norm (40%) and the national average (36%).
Labour market
Labour market pressures appear more pronounced in the region than elsewhere, with staff turnover cited as a growing challenge by 28% of businesses and the availability of non-management skills by 23%, both above the region's historical norms (20% for each) and the national averages (20% and 15% respectively).
In the context of these pressures and heightened labour cost concerns, annual employment growth in the West Midlands eased to 0.6% in Q3 2026, broadly in line with the 0.7% rate recorded nationally but below the region's historical norm (1.0%). Businesses plan to lift jobs growth to 1.4% over the next 12 months, above the regional norm and close to the 1.5% rise forecast for the UK.
Salary growth in the region picked up to 2.9% in the year to Q3 2026, slightly ahead of the UK rate (2.8%) and above the region's historical norm (2.1%). Companies expect pay growth to remain elevated at 2.8% over the coming year and maintain a gap to the UK forecast (2.6%).
Input and selling prices, and profits growth
Annual input price inflation in the West Midlands picked up to 4.2% in Q3 2026, its fastest rate since Q4 2025 and above both the region's historical norm (2.9%) and the UK rate (3.9%). Companies expect input cost growth to ease to 3.7% over the next 12 months, but this is notably above the 2.9% rise forecast for the UK, perhaps reflecting the more widespread concern about labour costs in the region and the greater dependence on energy for production.
Selling price growth edged up to 2.9% in Q3 2026, well above both the 2.2% national rate and the region's historical norm (1.6%), suggesting businesses in the region have passed on a larger share of their cost increases to customers than in most other parts of the UK. Companies plan to raise their prices by 3.2% over the next 12 months, among the strongest expected increases in the UK and ahead of the 2.1% national forecast.
Annual profits growth picked up to 2.7% in Q3 2026, broadly in line with the region's historical norm (2.8%) but below the 3.3% rate recorded nationally. Supported by the stronger sales and exports outlook, companies expect profits growth to accelerate to 5.3% over the next 12 months, well above the historical norm and the 4.5% rise forecast for the UK.
Capitial investment and R&D
Companies reported annual capital investment growth of 3.0% in Q3 2026, above both the region's historical norm (1.9%) and the national average (2.3%). However, amid continued global uncertainty, businesses plan to slow investment growth to 1.2% over the next 12 months, lagging both the regional norm and below the 2.0% rise forecast nationally.
Annual R&D growth eased to 1.3% in Q3 2026, below both the region's historical norm (1.8%) and the 2.3% rate recorded nationally. This is in contrast to the national trend and evidence from an ICAEW pulse survey that firms have increasingly focused on productivity and efficiency improvements to mitigate rising costs. Companies expect R&D growth to hold at 1.3% over the coming year, below the UK expectation (1.9%).
UK results
The UK Business Confidence Index rebounded to -0.5, from -14.6 in Q2, but remained negative for a seventh consecutive quarter. Current sales and profits proved resilient, but firms downgraded their expectations for both over the next 12 months. Geopolitical risk remained the leading challenge, while elevated input and labour costs continued to put pressure on margins. Energy costs, regulations and the tax burden remain significant challenges. The rebound was broad but uneven: confidence rose in every sector, IT & Communications was the most positive, while Property and Construction remained deeply negative.
The latest quarterly findings are based on the period 13 July to 21 September 2026.